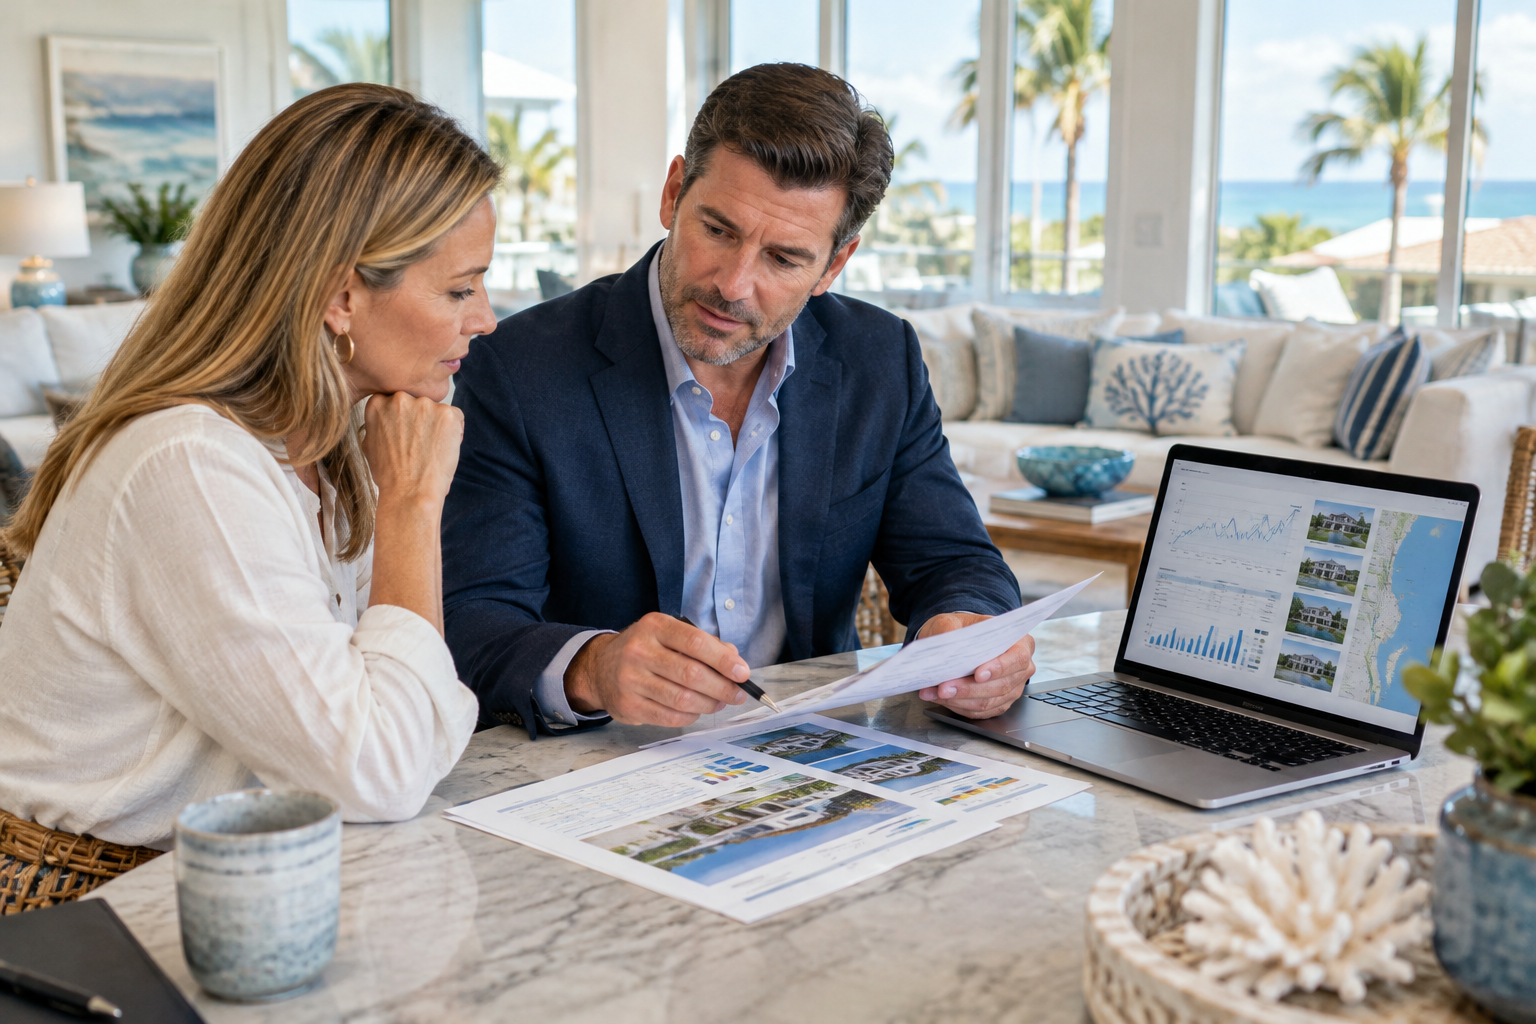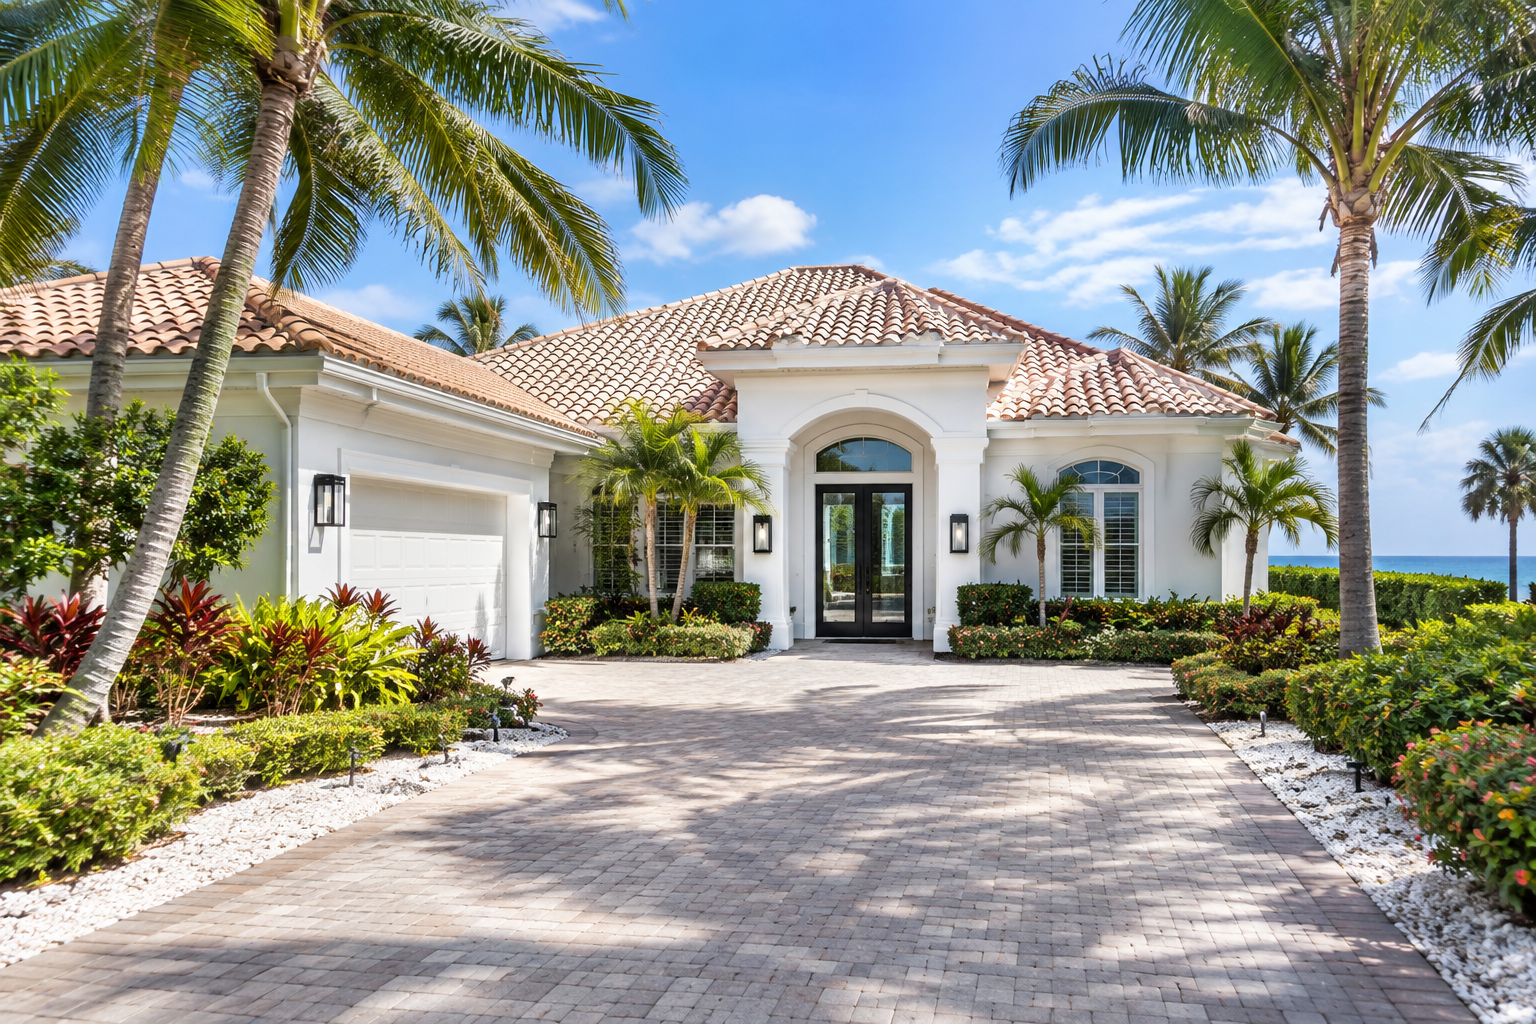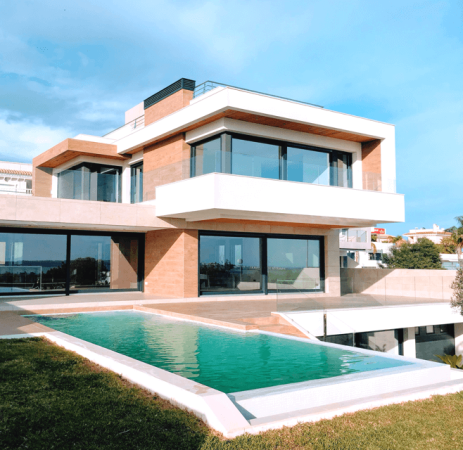
In Vero Beach’s 32963 oceanfront market, the difference between a strong offer and a smart acquisition often comes down to documents that never appear in the listing photos. A house may show beautifully from A1A or the dune crossover, but the real risk profile is determined by flood zone, wind coverage, roof age, opening protection, and how the structure sits relative to base flood elevation. Prospective purchasers can explore active listings directly through our Vero Beach luxury waterfront estates portfolio.
Why Underwriting Often Changes the Real Price of a 32963 Oceanfront Home
For high-value oceanfront homes on the barrier island, insurance underwriting is not a formality; it is part of the acquisition math. Carriers evaluate more than square footage and replacement cost. They look at the age of the roof, the presence of impact-rated glazing, the quality of shutters, the condition of the garage door, and whether the home has a clear wind mitigation story from the top of the ridge line down to the foundation. On direct Atlantic frontage, even an elegant remodel can be priced aggressively if the roof deck attachment, secondary water barrier, or opening protection cannot be documented.
Flood insurance adds another layer. Many buyers assume that a seawall or elevated living area automatically reduces the burden, but flood carriers and lenders focus on the actual elevation certificate and the specific flood zone designation. In parts of the barrier island, VE zones can drive substantially higher premiums than AE zones, especially when the lowest floor is near the minimum required elevation. If the property has an enclosed lower level, a garage, or a bonus room built below the main living level, the premium picture can change quickly.
Waterfront living extends across the barrier island’s dining, arts, and waterways, as highlighted in the local Vero Beach lifestyle guide. That lifestyle premium is part of what draws buyers to the coast, but it should be balanced against the recurring cost of insuring a luxury asset exposed to salt air, wind events, and storm surge. In practice, the annual carrying cost on a premier oceanfront estate can shift meaningfully based on underwriting class, deductible structure, and whether the buyer is entering the market with cash or a mortgage that triggers lender-required flood placement.
Elevation Certificates and Wind Mitigation Reports: The Documents That Move the Deal
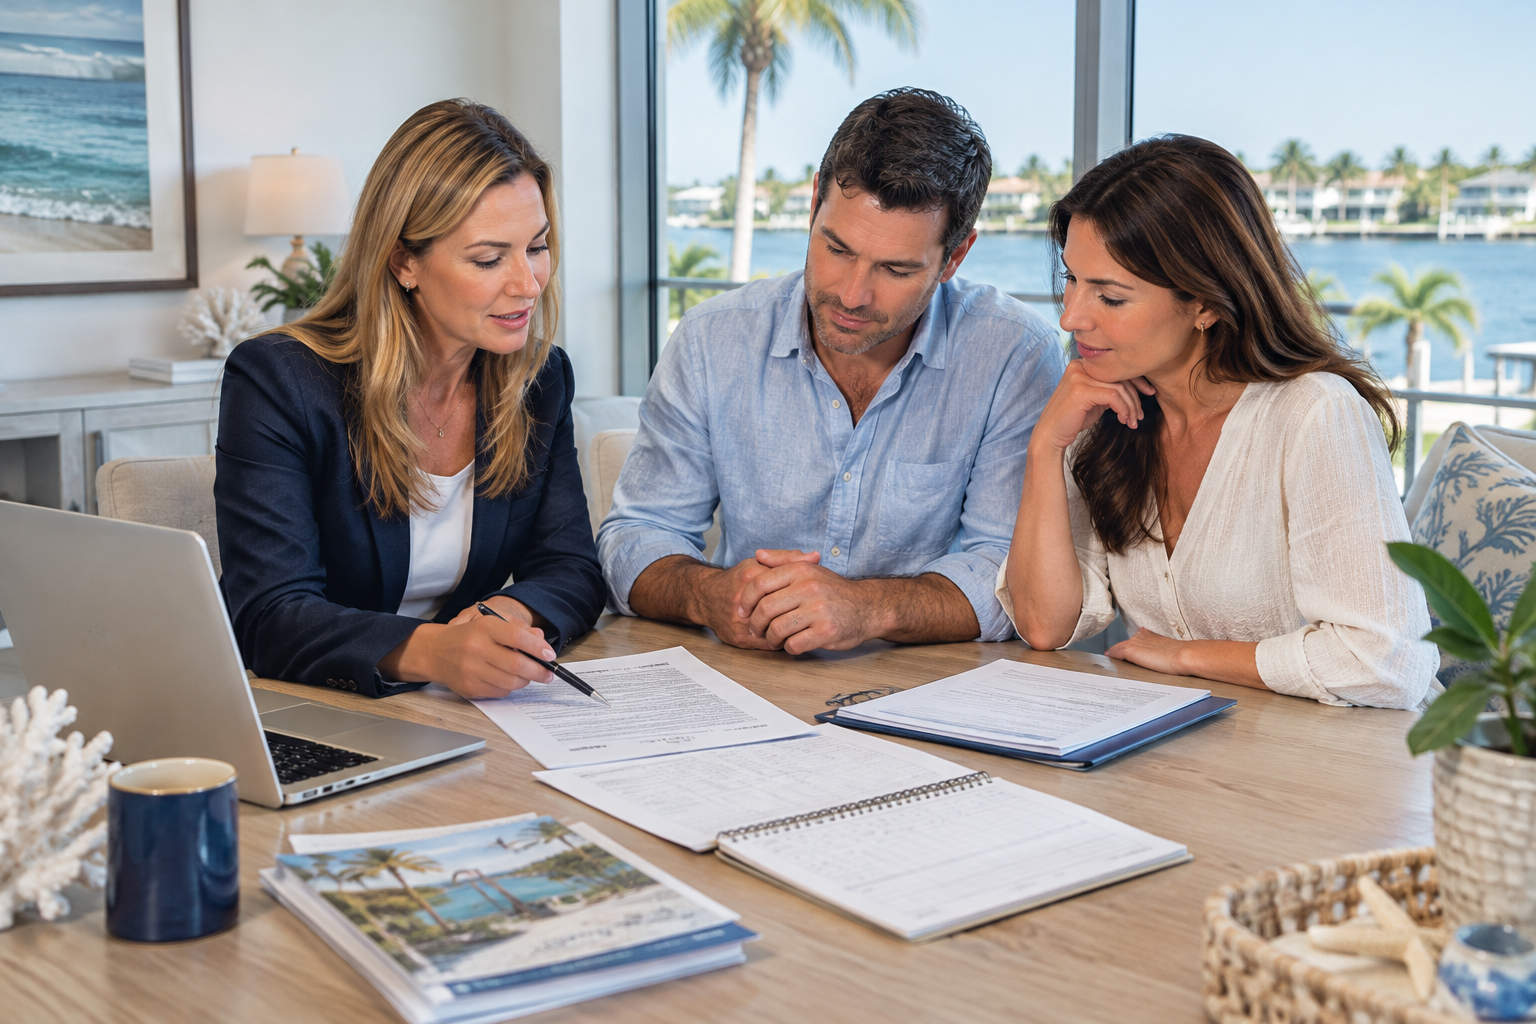
In Indian River County, the most useful pre-contract documents are often the least glamorous. An elevation certificate tells the buyer where the home actually sits in relation to the surveyed flood benchmarks, while a wind mitigation report identifies the features that may qualify for premium credits. These reports should be reviewed before contingency deadlines, not after. If the certificate is outdated, inaccurate, or based on a prior configuration, the buyer may not learn the true risk until the insurer quotes the policy.
Key items include the finished floor elevation, the lowest adjacent grade, the lowest opening, and any variance between the survey and the county record. Buyers should also verify whether improvements such as decks, additions, seawall work, or rebuilt stair systems altered the structure in a way that affects insurability. A property that appears turnkey may still require a correction letter from a surveyor or engineer before the lender and carrier will accept the file.
Shoreline protection and structural standards are detailed thoroughly in our Vero Beach coastal buying guide.
Wind mitigation matters just as much. Florida carriers may credit a hip roof, proper roof-to-wall connections, impact openings, and secondary water resistance. For a luxury oceanfront buyer, those credits are not merely nice-to-have discounts; they can determine whether the annual premium remains manageable enough to hold the property comfortably over time. The best time to negotiate these issues is before inspection contingencies expire, when repair estimates or documentation gaps still provide leverage.
Four Due-Diligence Steps Before You Remove Contingencies
- Order the elevation certificate immediately. Confirm the exact finished floor elevation, lowest opening, and flood zone designation before you finalize insurance assumptions.
- Request the wind mitigation inspection and roof documentation. Verify roof age, installation records, straps, clips, shutters, impact glass, and any secondary water barrier credits.
- Get insurance quotes from more than one source. Compare admitted carriers and surplus lines options, and review deductibles, exclusions, and named-storm exposure carefully.
- Review any shoreline or structural maintenance history. Seawalls, docks, dune work, and past repairs should be evaluated for permit compliance, long-term durability, and lender comfort.
On the barrier island, these steps are not busywork; they are the difference between owning a showpiece and owning a financial liability. A buyer who understands the data can negotiate price, request credits, or walk away from an asset whose insurance load is out of proportion to its appeal.
Final Considerations for Vero Beach Luxury Waterfront Buyers
For specialized representation across Indian River County, consult our advisors for buying real estate in Vero Beach. The strongest oceanfront purchases are made by buyers who treat insurance, elevation, and mitigation as part of the property itself, not as paperwork afterthoughts. A home on the Atlantic can be exceptional in location, design, and lifestyle value, but only if its risk profile is understood before closing. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.