Vero Beach rental owners do not lose margin from one dramatic event; they lose it from small misreads in flood-map status, reserve planning, and vendor response time. A mainland duplex in an X zone can look safer on paper than a barrier-island condo in 32963, but once HOA assessments, coastal insurance, and salt-air wear enter the model, the real question becomes which asset will keep producing net income after repairs, compliance, and vacancy are priced correctly.
Set the exchange target against actual Vero Beach rent math
For a portfolio owner using a deferred exchange, the replacement property should be evaluated by stabilized NOI, not just by asking rent or frontage. In Indian River County, a two-unit or four-unit asset on the mainland often delivers better operational control than a waterfront condo, yet a high-quality barrier-island unit can still win if insurance, reserves, and association dues leave enough spread after debt service. That is why a disciplined 1031 Exchange plan starts with rent-roll verification, lease-expiration timing, and a replacement-property budget that includes flood certification, wind-mitigation credits, and a conservative allowance for vacancy between tenants.
Buyers should also separate tax deferral from long-term asset quality. If a property’s income depends on annual rent spikes to justify the basis, the deal is fragile; if it supports market rent at modest occupancy loss, it is more resilient. In Vero Beach, that usually means looking closely at unit mix, parking, laundry income, utility responsibility, and how the asset performs in both AE and X flood zones when lenders, insurers, and appraisers take a harder look.
Build a maintenance and compliance calendar around salt air, licenses, and milestones
Coastal maintenance in Indian River County is not a seasonal nuisance; it is an underwriting line item. Salt air shortens the life of exterior fasteners, railings, HVAC condensers, gate hardware, and balcony components, so vendor coordination should be built into a recurring schedule instead of handled as emergency work. Owners who run multi-family assets from a distance need documented inspections, photo logs, and vendor scopes that keep corrosion from turning into capital expense. That is also where Property Management Compliance matters, because Florida real estate license law can affect who is marketing the property, collecting rents, negotiating leases, and supervising day-to-day management.
For condos and HOAs, milestone reports, reserve discussions, and structural review timelines deserve as much attention as paint and landscaping. A building may carry good occupancy today and still face future cash calls if balconies, roofing systems, or concrete restoration were deferred too long. On the barrier island, one missed association disclosure can erase months of projected yield, while a mainland property with cleaner governance and lower exposure may produce steadier returns even at a lower headline rent.
Four-point due-diligence checklist for landlord and investor buyers
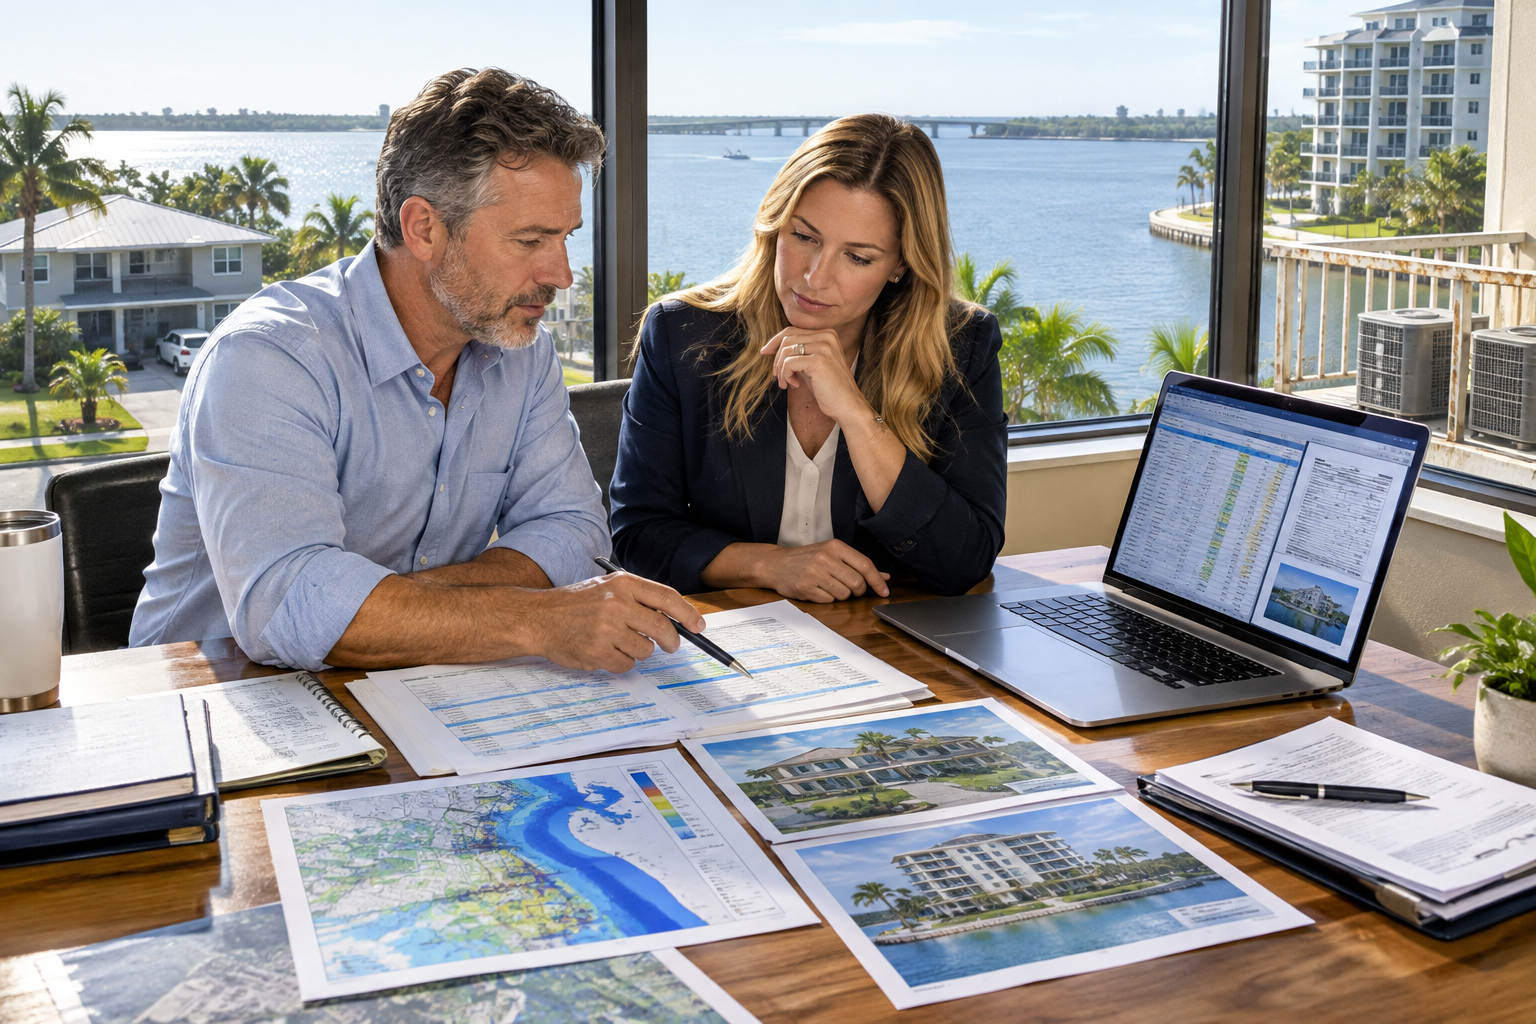
- Confirm the flood zone designation for every building, unit, and improvement, then test insurance quotes against AE and X scenarios before offering.
- Review the last 12 months of rent rolls, delinquency history, lease renewal timing, and turnover costs to see whether income is truly stabilized.
- Verify who will handle leasing, maintenance supervision, and rent collection, and make sure the management structure complies with Florida licensing rules.
- Request association budgets, reserve studies, milestone reports, and recent special assessments for any condo or HOA property before final underwriting.
Final Considerations for Vero Beach Buyers
The strongest coastal investment is rarely the property with the flashiest brochure; it is the one whose income, maintenance profile, and legal structure all survive closer scrutiny. In Vero Beach, that means comparing mainland and barrier-island opportunities through the same lens: flood exposure, insurance cost, association stability, vendor reliability, and the ability to keep tenants in place without recurring surprises. Investors who build their acquisition process around those realities are far better positioned to protect cash flow, preserve basis through a 1031 exchange, and avoid the most common mistakes that erode returns in Indian River County.
FAQ
What should a Vero Beach investor verify before placing a duplex under professional management?
Verify the owner’s licensing path, the lease forms used, maintenance authority, rent collection procedures, and whether the manager can legally perform the services promised under Florida real estate rules. It is also smart to confirm how the manager documents inspections, vendor invoices, and tenant communications for audit and insurance purposes.
How do flood zone and condo milestone reports change underwriting on the barrier island?
Flood zone status affects insurance pricing, lender requirements, and reserve assumptions, while milestone reports can signal future capital calls or structural work that should be reflected in the purchase price. Those items can change the deal faster than a one-time rent increase, which is why coastal buyers in 32963 should underwrite them before committing to a closing timeline. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.