A Vero Beach move can change your tax bill, insurance cost, and school plan in one stroke, but only if you line up domicile, homestead filing, utility service, and neighborhood selection with the county’s rules before the calendar works against you.
Establishing Domicile Before the Deadline Matters More Than the Closing Date
For Florida buyers, the homestead clock is tied to permanent residence, not simply the day you get the keys. To claim a primary-residence exemption for the tax year, the home must be your permanent residence on January 1, and the application generally must reach the Indian River County Property Appraiser by March 1. Establishing Florida Domicile is not a formality; it is the paper trail that proves the property is your true home, while the Homestead Exemption can reduce the taxable assessed value on qualifying property.
Buyers coming from another Florida county should also ask whether Save Our Homes portability applies. If you owned and lived in a prior Florida homestead, part of your capped assessed value may transfer to a new Vero Beach residence, but the benefit depends on filing correctly and within the applicable window. That matters for both mainland homes and 32963 properties because the tax delta can be substantial once market value, assessment caps, and millage rates are all in play.
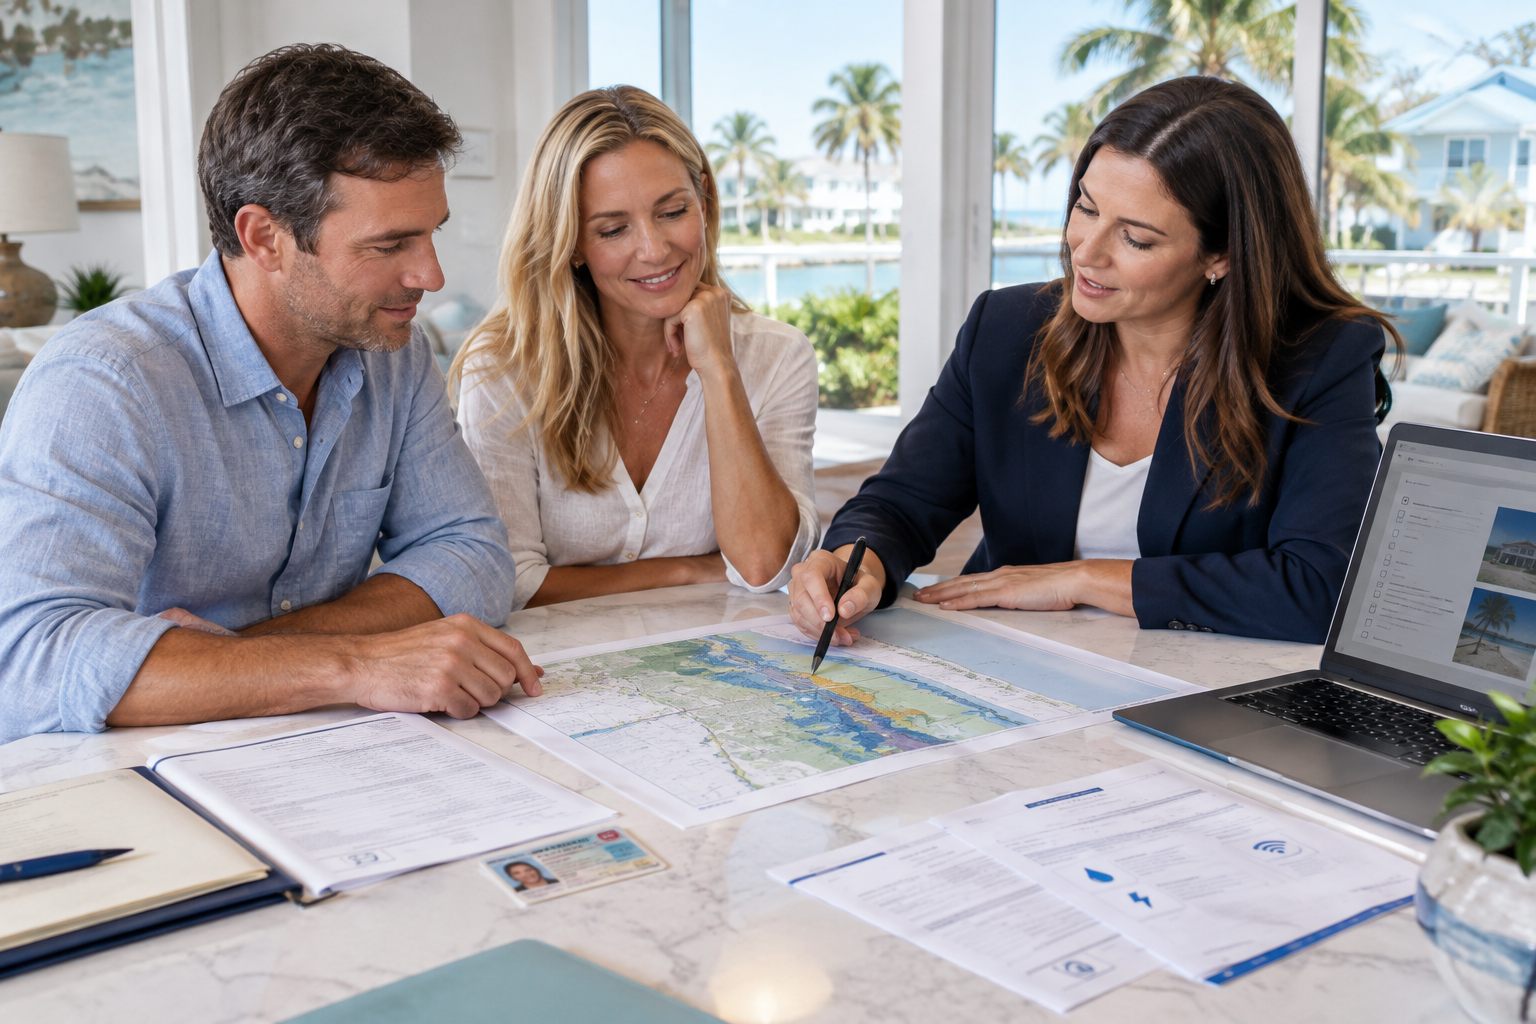
Strong domicile evidence helps avoid problems later. Update your driver license, voter registration, vehicle registration, insurance address, and financial records; if needed, record a declaration of domicile. When a closing spans late December into January, timing becomes critical because a home purchased too late may miss the current tax year’s homestead opportunity even if the intention to move is genuine.
Mainland vs. 32963: Utilities, Flood Risk, and School-Zone Logistics
Vero Beach utility planning is rarely one-size-fits-all. Some properties rely on FPL for power, while water and sewer service may come from the City of Vero Beach, Indian River County systems, or private providers depending on the parcel. Before closing, confirm meter status, connection fees, irrigation service, septic vs. sewer, and whether any buried or shared infrastructure will need repair or inspection. A clean inspection report can still leave a buyer with expensive surprises if the seller’s utility setup was patched together over time.
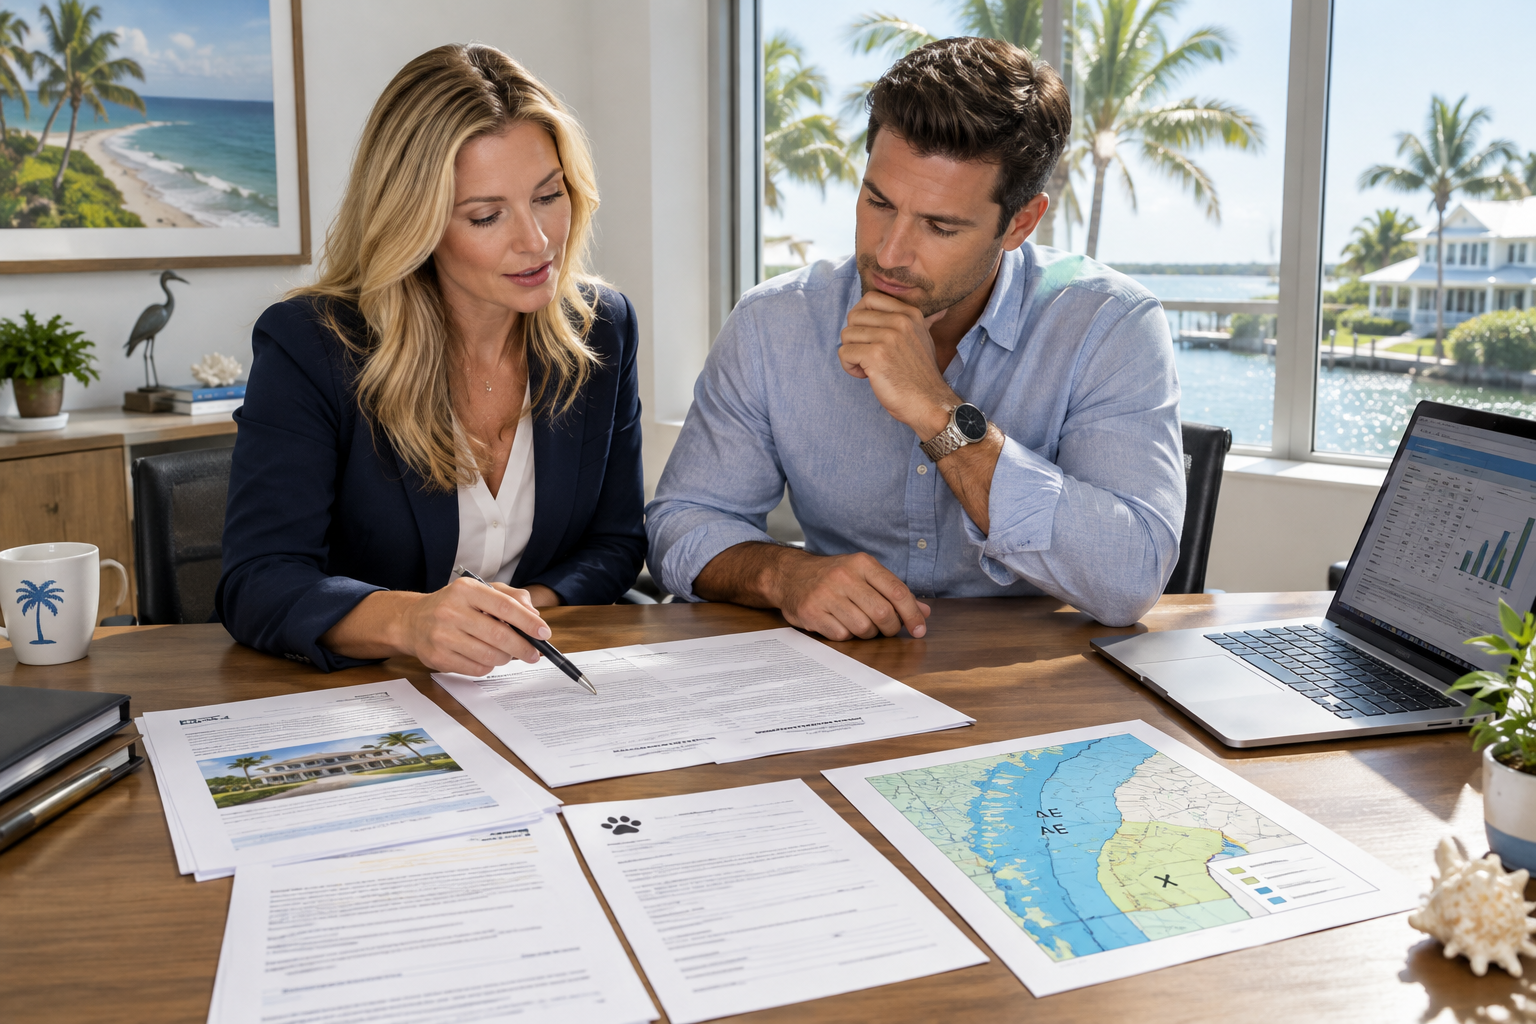
Flood exposure also changes the monthly carrying cost. On the barrier island, especially in 32963, buyers should verify whether the property sits in Flood Zone AE or X, request an elevation certificate when available, and obtain insurance quotes early. Zone X is generally considered lower risk than AE, but no coastal address should be underwritten casually. Barrier island homes can carry higher wind and flood premiums, and condos add another layer of due diligence: review reserves, association budgets, milestone inspections, and any special assessments before you assume the monthly payment is fixed.
Mainland neighborhoods often offer more flexibility for lot size, parking, storage, and commuting, while the island can offer proximity to the ocean with tighter HOA or condo controls. If schools are part of the move, verify the assigned public school with the School District of Indian River County before you sign, especially if you are trying to land in a specific attendance zone. Families moving midyear should compare the public-school start date, private academy enrollment deadlines, and bridge traffic patterns so the commute and transition do not become the weak link in the purchase.
Relocation and Due-Diligence Checklist
- Confirm that the property can support your homestead timeline, then gather domicile documents before the March 1 filing deadline.
- Order flood-zone, elevation, and insurance quotes early, with special attention to AE versus X and any condo or HOA assessment history.
- Verify utility providers, meter status, sewer or septic configuration, and any county or city connection requirements before closing.
- Cross-check school zones, commute times, and HOA or deed restrictions so the neighborhood fits your long-term plan, not just the listing photos.
Final Considerations for Vero Beach Buyers
The strongest Vero Beach purchases are the ones where the tax strategy, utility setup, flood profile, and neighborhood fit are evaluated together instead of one at a time. Mainland and barrier-island homes can both make sense, but they carry different costs and rules, and those differences become more important when you are establishing Florida residency, seeking homestead relief, or moving children into a new school system. A well-timed purchase can improve your tax position and simplify daily life; a rushed one can leave you paying for avoidable insurance, assessments, or zoning conflicts long after closing. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.
Frequently Asked Questions
When should I file for homestead exemption after buying in Vero Beach?
File as soon as you have established your permanent residence, and do not miss the March 1 deadline for that tax year. The property must also be your permanent residence on January 1 to qualify for that year’s exemption.
Is it usually more complicated to buy on the barrier island than on the mainland?
Often yes. Barrier-island purchases can involve higher flood and wind costs, tighter HOA or condo rules, and more detailed due diligence on assessments and reserves. Mainland homes may be simpler on utilities and restrictions, but every property should be checked individually.