In Vero Beach, the biggest financing surprises rarely show up in the pre-approval letter; they surface when a jumbo file meets coastal reality on the barrier island, the mainland, and the closing table all at once. A lender may be satisfied with income, assets, and credit, but a home in 32963 with an AE flood designation, a condo subject to active association review, or a title file waiting on estoppel figures can still slow the transfer of ownership. Buyers who understand how underwriting, Florida closing taxes, and insurance-related escrow holdbacks interact are much less likely to lose time, money, or leverage during the final stretch.
How Jumbo Underwriters Read Coastal Risk in Indian River County
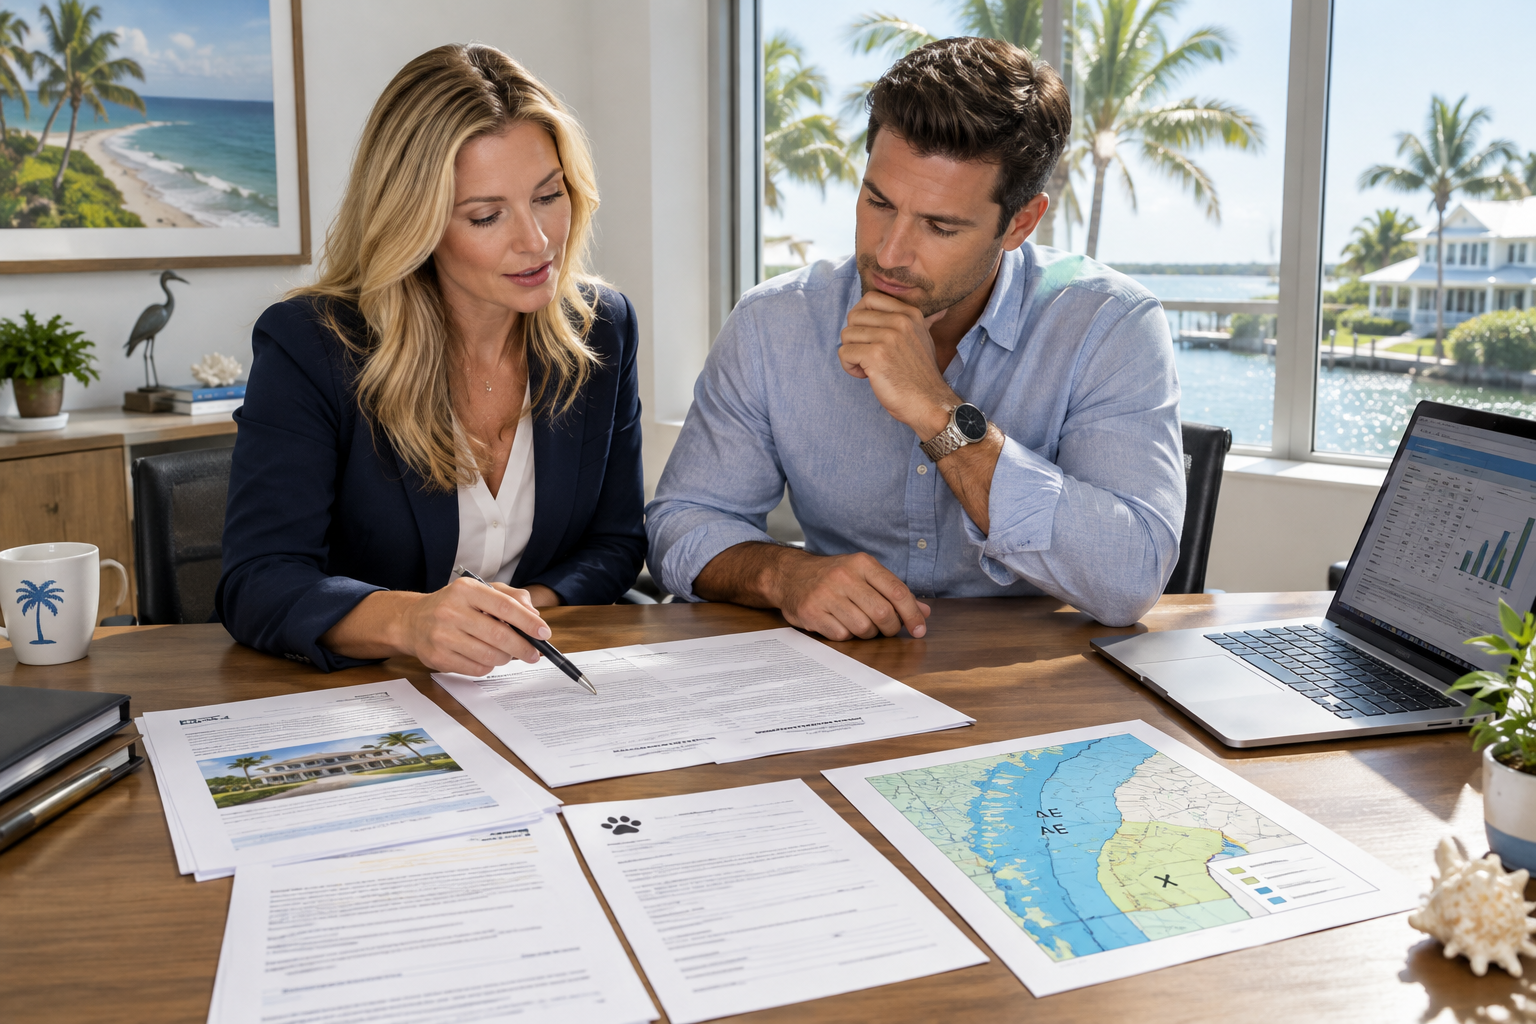
For a coastal property, a jumbo loan is not judged only on borrower strength; it is also judged on the home’s insurability, marketability, and recoverability after a storm event. That means underwriters scrutinize flood maps, elevation data, roof age, wind mitigation features, and any evidence that the property sits in a higher-risk exposure corridor near the Indian River Lagoon or the Atlantic side of the county. A residence in an AE flood zone may still finance cleanly, but the file often requires stronger reserves, a lower debt-to-income ratio, and a fully documented insurance quote before final approval. By contrast, an X zone property may reduce friction, yet it does not eliminate the need for hazard, wind, and sometimes flood coverage if the lender’s risk model or carrier requires it.
Borrowers should also expect tighter scrutiny when the property is a condo or part of a homeowners’ association, especially if the building is older, has deferred maintenance, or is in the middle of a reserve and inspection review. That is where Jumbo Mortgage Underwriting and HOA Estoppel Letters become more than back-office paperwork; they directly affect whether the lender can confirm the association’s financial health and whether the title company can issue a clean closing package. In Indian River County, a last-minute mismatch between the lender’s requirements and the association’s response time can push closing dates even when the buyer is fully qualified.
The Closing Cost Items Buyers Miss Until the Settlement Statement Arrives
Florida buyers often focus on price and down payment, but the final cash-to-close number can change materially because of documentary stamp tax, intangible tax on new mortgages, lender fees, title charges, prepaid insurance, and prorations for property taxes and HOA dues. On a coastal purchase, the insurance line item deserves special attention because carriers may require roof inspections, four-point inspections, wind mitigation documentation, or temporary holdbacks if a repair or certification is still pending. If the underwriter allows an escrow holdback, the lender will generally require a written scope of work, a contractor timeline, and a reserve amount sufficient to protect the collateral until the issue is resolved.
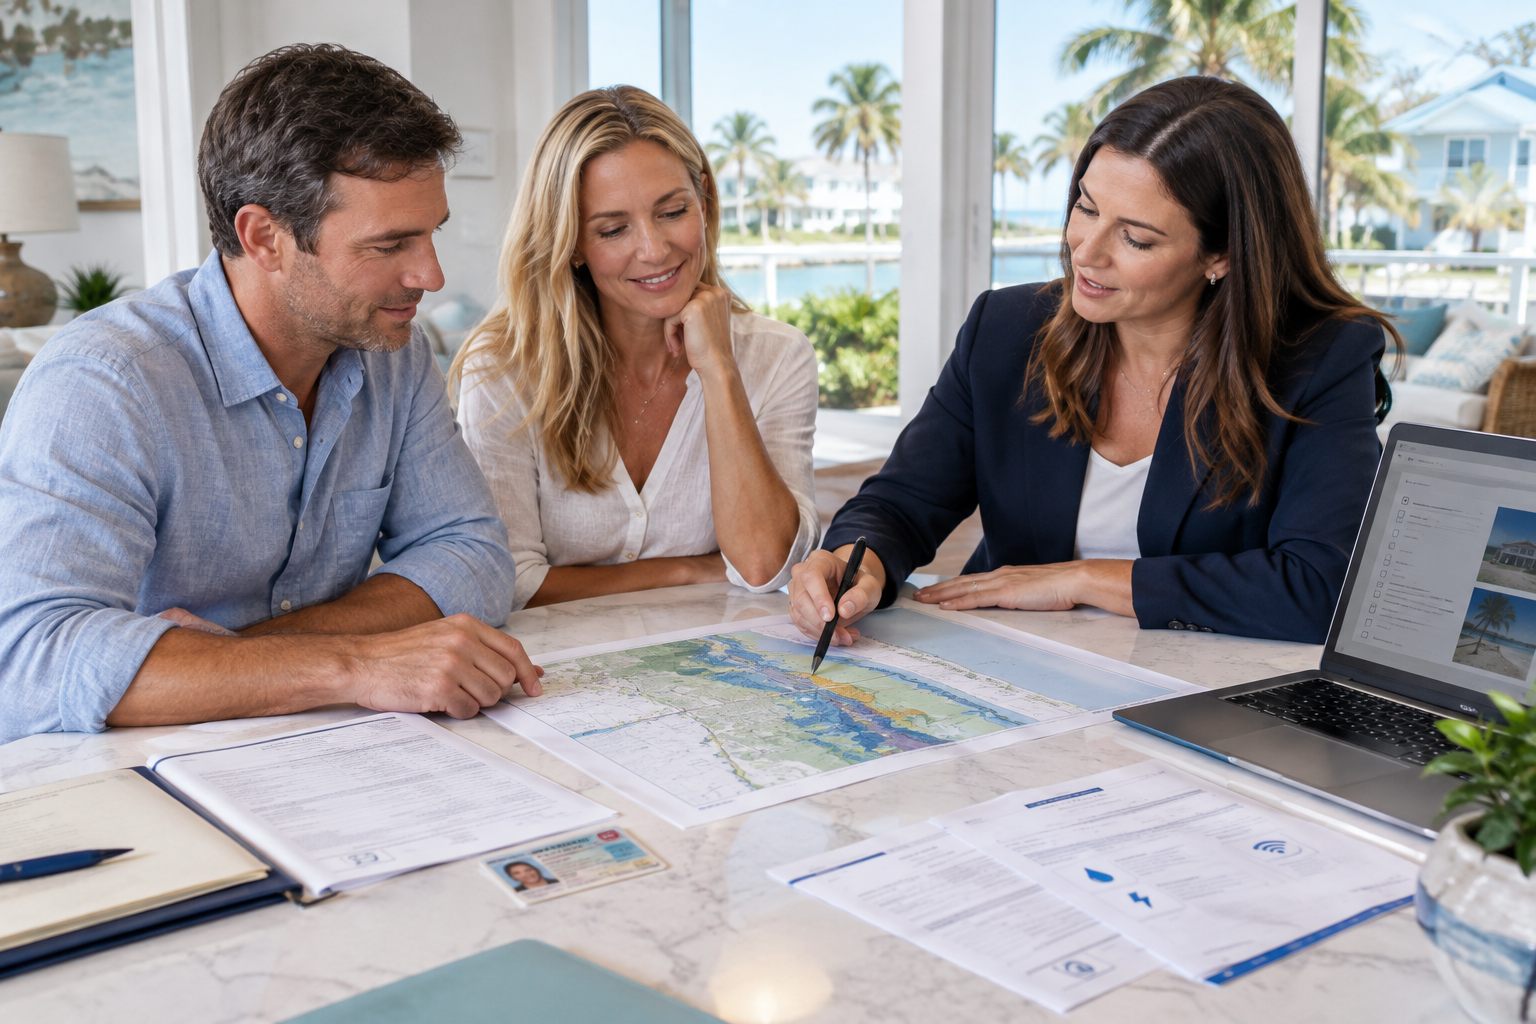
That is also where proof-of-funds verification matters for cash buyers. A buyer bringing cash to a Vero Beach transaction should be ready to document liquid funds, account ownership, and any large transfers well before the closing date. Title agents and sellers in this market expect clean verification, especially on barrier island listings where multiple offers are common and sellers want certainty. When buyers combine cash with a later refinance strategy, lenders may still examine source-of-funds documentation, seasoning, and the path of the money into the closing account. Accurate cash planning reduces the chance of a delayed wire, a missing bank letter, or a scramble to satisfy a compliance request at the eleventh hour.
A 4-Point Due-Diligence Checklist Before You Sign in Vero Beach
- Confirm the flood zone and insurance path early. Verify whether the property is AE, X, or otherwise affected by lender flood requirements, then obtain realistic quotes for wind, hazard, and flood coverage before removing financing contingencies.
- Ask for association documents immediately. For condos and HOA properties, request the estoppel, budget, reserve data, master insurance evidence, and any inspection or milestone-related materials as soon as the offer is accepted.
- Request a preliminary closing estimate with taxes and lender charges included. Make sure documentary stamp tax, intangible tax, title insurance, recording fees, and prepaid items are calculated using the correct loan amount and contract terms.
- Verify source of funds or reserve strength before underwriting deepens. Whether you are financing or paying cash, organize bank statements, asset statements, gift letters if applicable, and any liquidity documentation the lender or title company may request.
## Final Considerations for Vero Beach Buyers
A smooth coastal closing in Vero Beach depends on more than loan approval; it depends on whether every piece of the file tells the same story about the property, the buyer, and the risk profile of the transaction. Jumbo loans, Florida transfer taxes, insurance holdbacks, and association estoppels can all move a purchase from easy to complicated if they are not handled early and in the right order. Buyers who treat flood zone status, condo review, title clearance, and cash verification as part of the same process gain the best chance of closing on time and with fewer surprises. In a market shaped by the barrier island, the mainland, and the realities of coastal insurance, local experience is not optional.
FAQ
How does an AE flood zone affect jumbo financing in Vero Beach?
An AE designation does not automatically prevent financing, but it usually means the lender will require flood insurance and may scrutinize the file more closely for reserves, elevation, and overall insurability. Buyers should expect the insurance quote to be part of underwriting, not an afterthought.
Why can an HOA estoppel delay a Florida closing?
An estoppel confirms what the seller owes the association and whether the account is current. If the association is slow to respond, or if the figures reveal unpaid amounts, the title company may have to hold closing until the payoff is verified and all obligations are cleared.
For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.