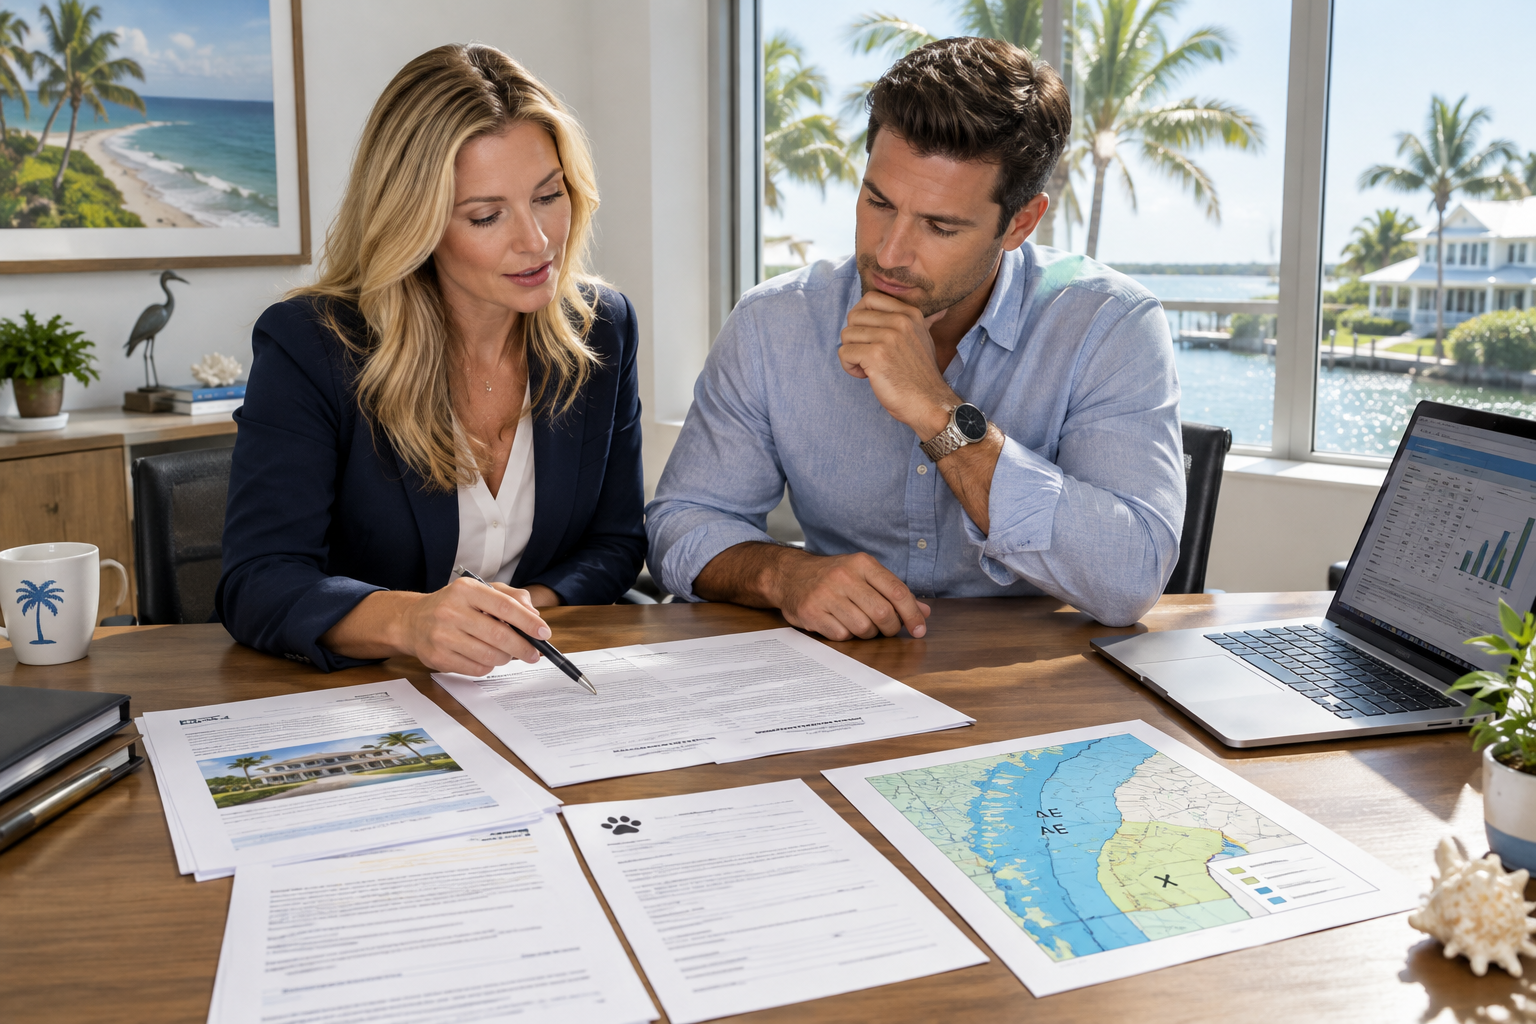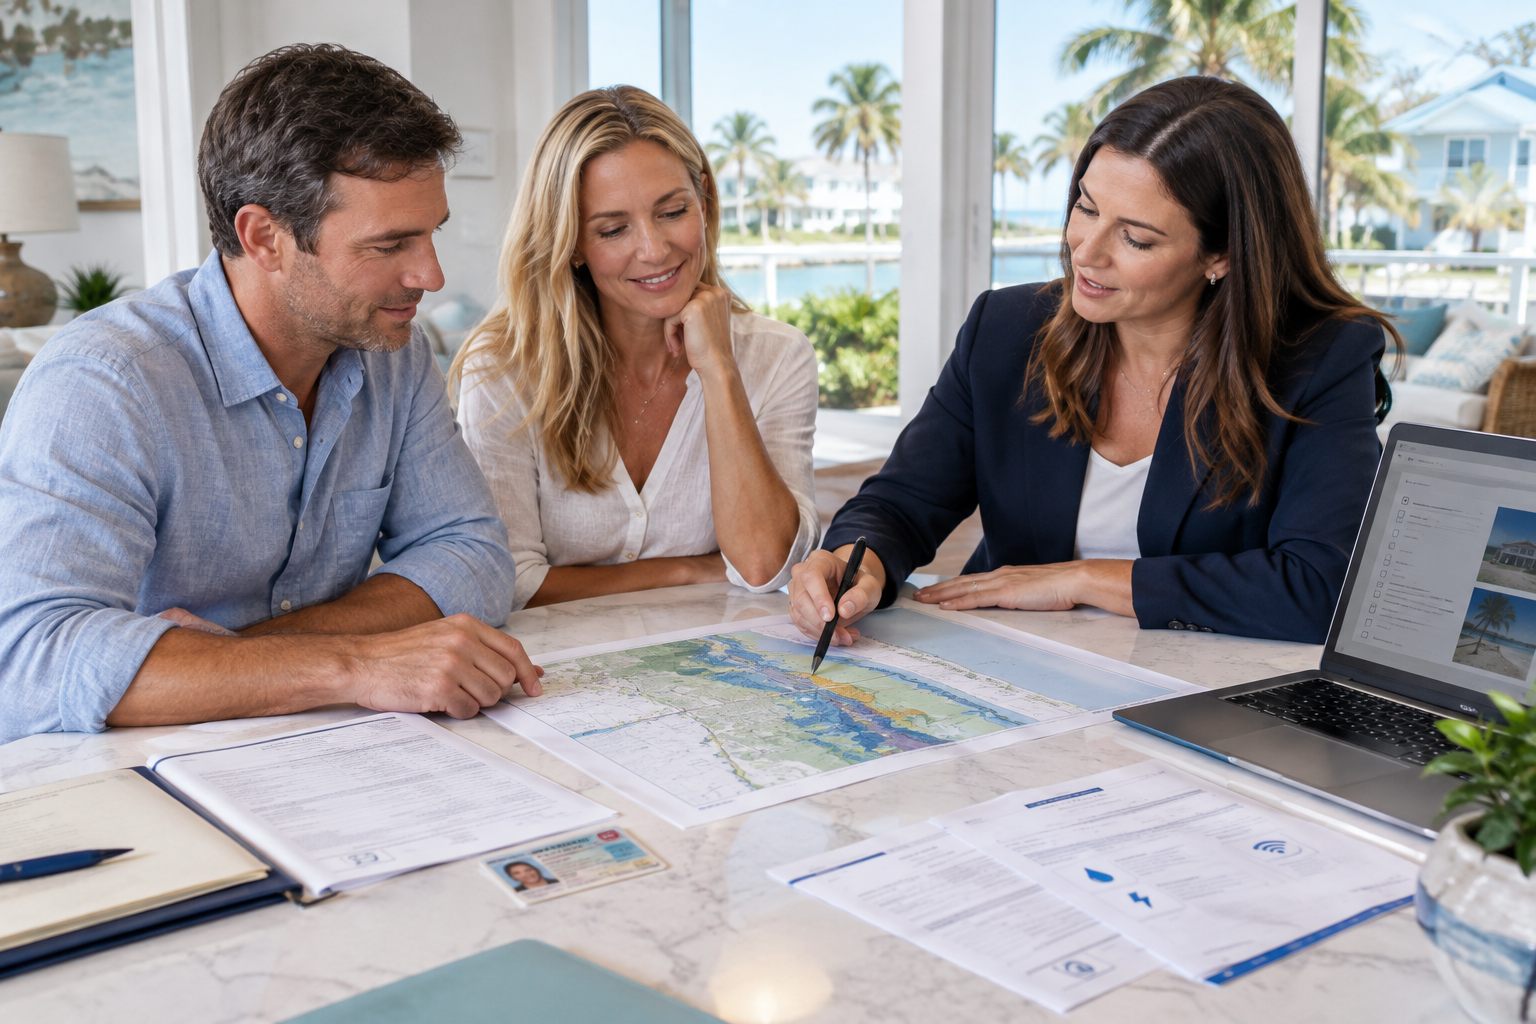
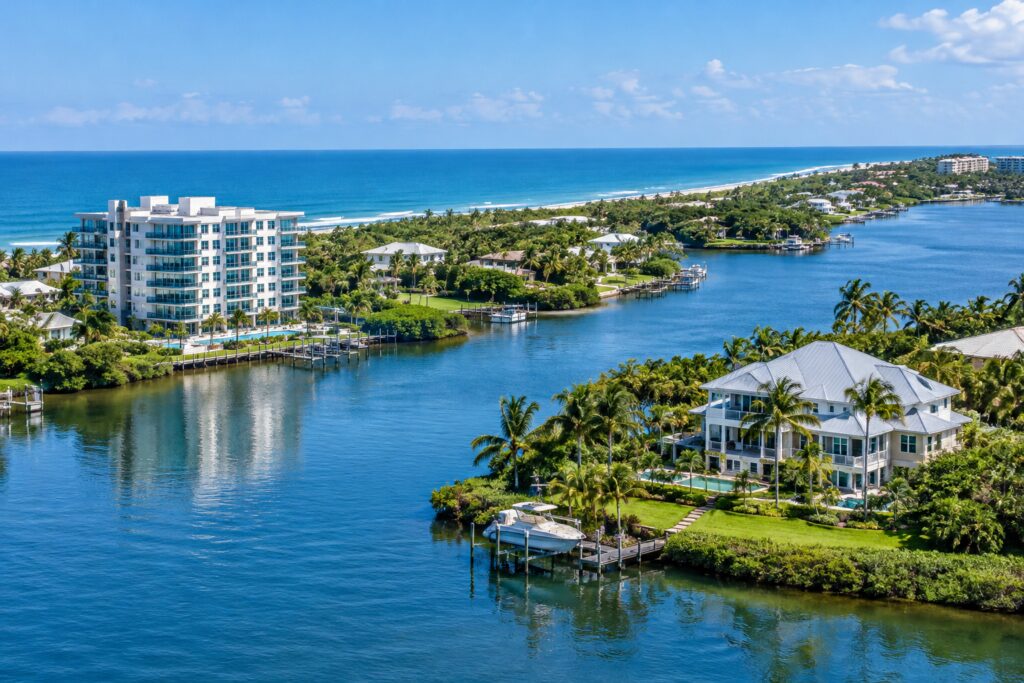
Vero Beach‘s strongest pricing divide this month is not between waterfront and non-waterfront; it is between the 32963 barrier island and the mainland zip codes where financing, insurance, and property type create very different market tempos. On the coastal side, buyers are still paying a premium for proximity to the Atlantic and the Indian River Lagoon, but they are also asking harder questions about flood zone AE versus X, condo reserves, milestone inspections, and projected carrying costs. On the mainland, move-up homes in 32960, 32962, 32966, and 32967 are often attracting more immediate attention because the price entry point is cleaner, the insurance conversation is simpler, and well-presented listings can compete on value instead of just lifestyle.
Inventory Is Fragmented, Not Uniform
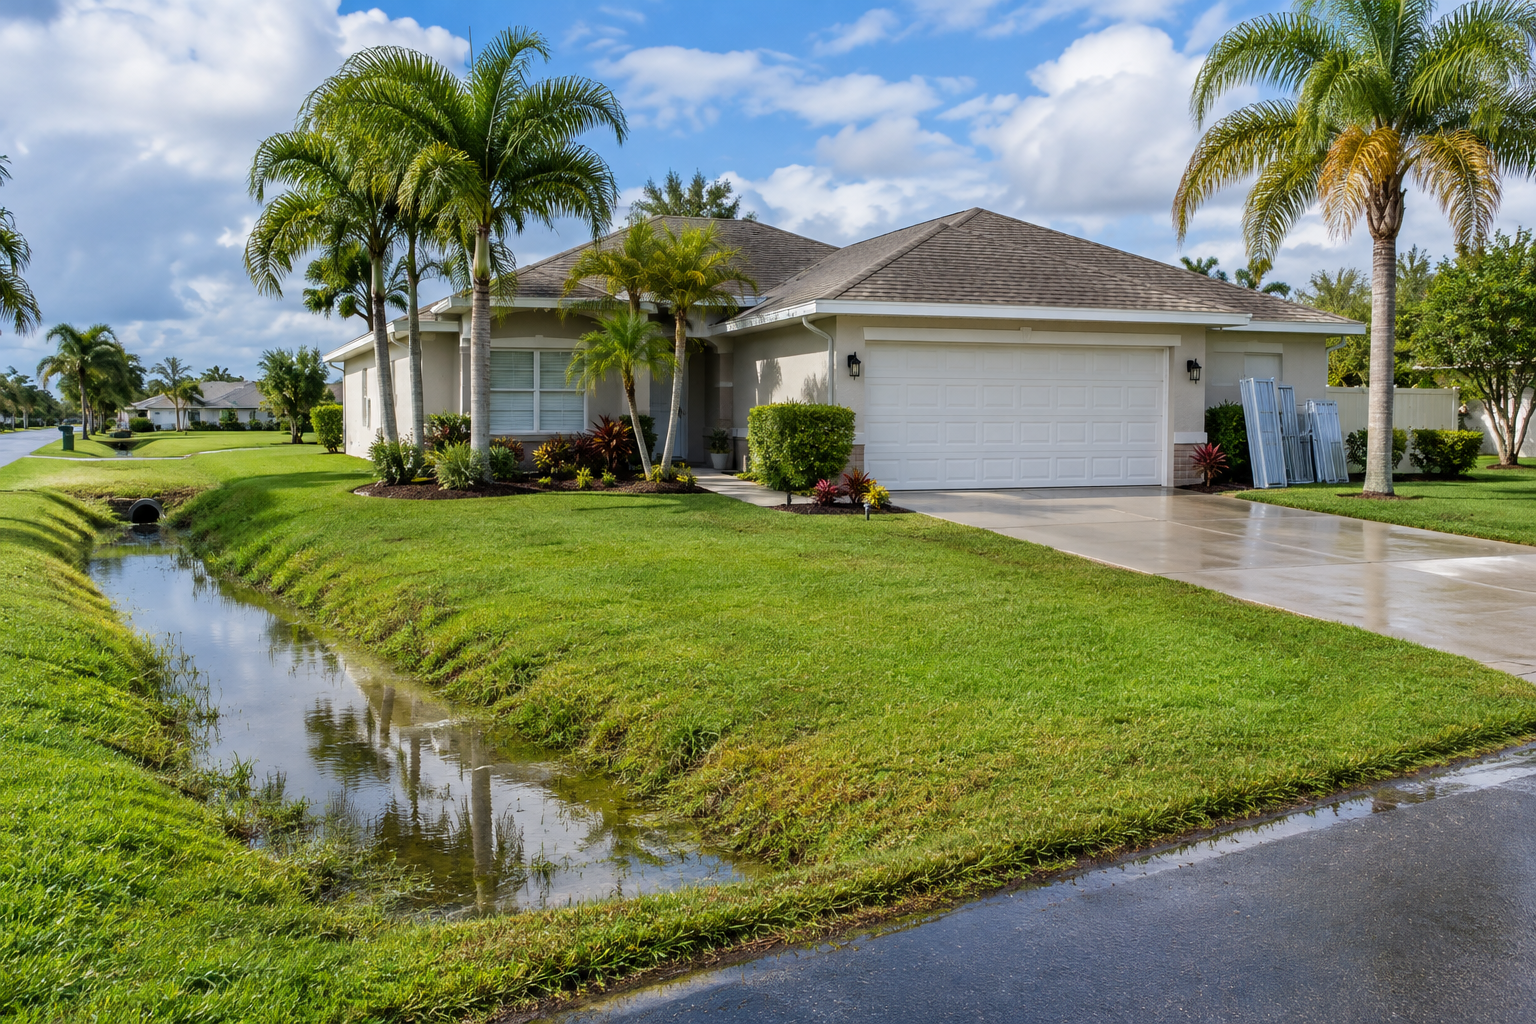
The smartest read on Housing Inventory is by micro-market, not by countywide average. A month of supply for an updated inland single-family home near schools and services does not tell you much about a riverfront condo building with an active reserve review or a barrier-island residence that must clear elevation, wind, and flood underwriting. In practice, the mainland often shows faster absorption because more financed buyers can qualify comfortably, while 32963 can carry a longer supply tail whenever a building’s assessment history, insurance cost, or age pushes buyers to pause. That same split shows up in Days on Market: clean, correctly priced mainland homes can move quickly, while coastal listings need sharper presentation, stronger disclosures, and a more patient pricing strategy.
For sellers, the takeaway is straightforward. Inventory that looks