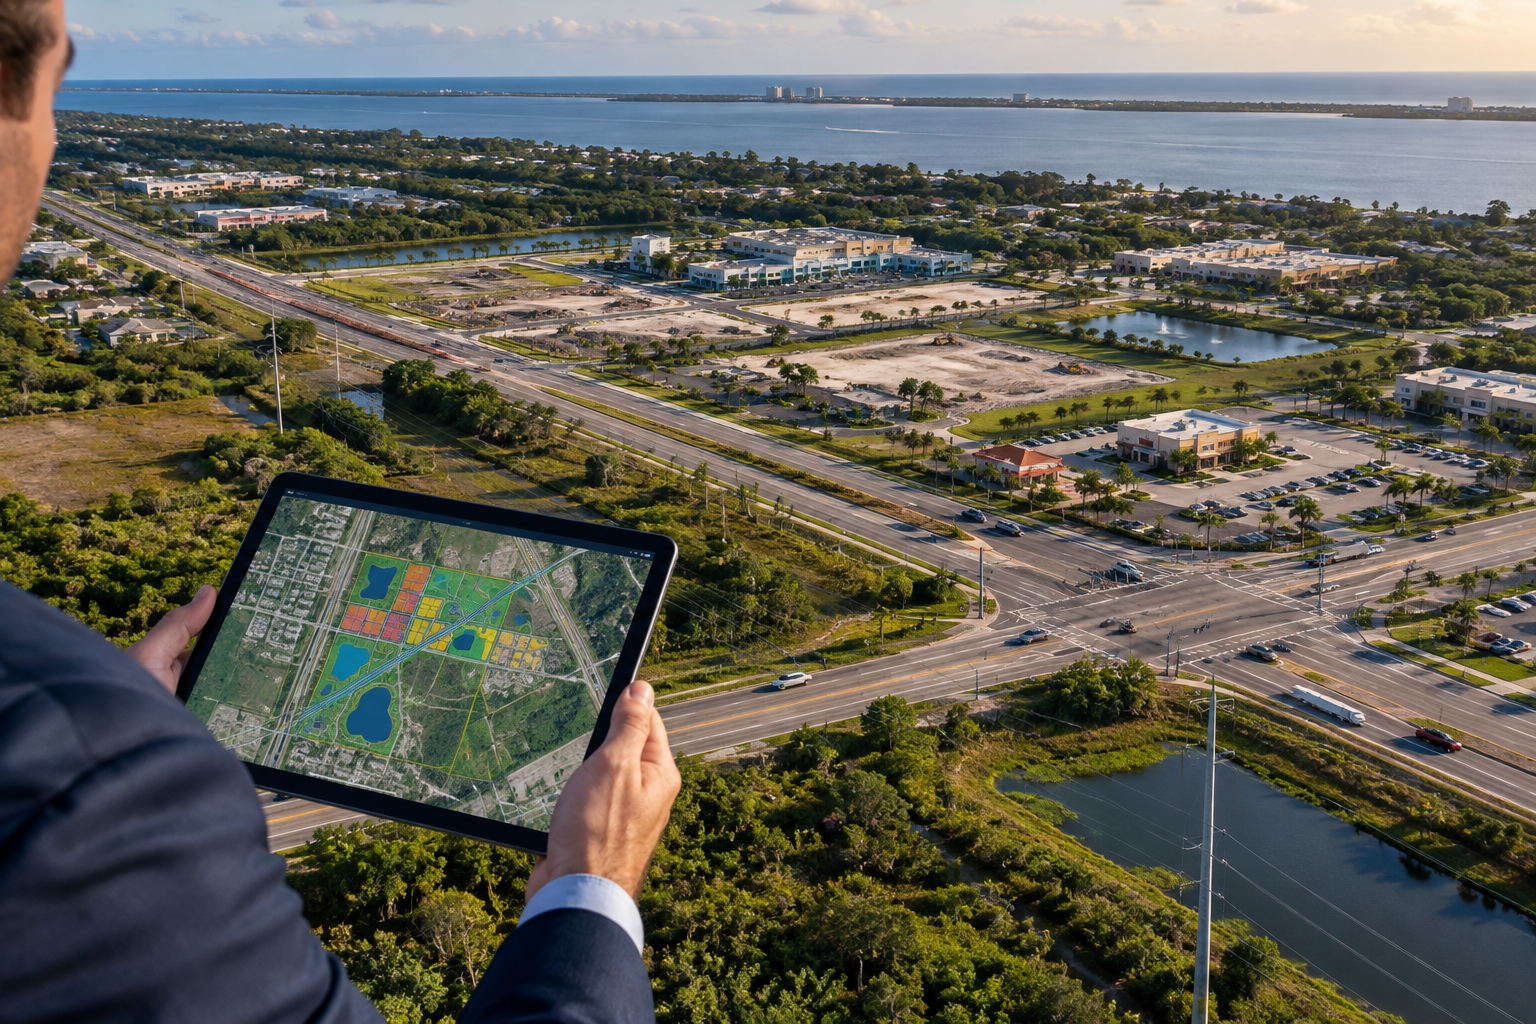
On Vero Beach‘s mainland, the smartest single-family purchase is not always the one with the newest finishes or the biggest yard; it is the one that manages water, wind, and setbacks correctly from day one. Along 58th Avenue, Route 60, and into the acreage pockets near Sebastian and Fellsmere, buyers who understand drainage swales, flood zones, and roof-to-foundation construction standards can separate a well-built long-term hold from a property that looks affordable until the first heavy rain or insurance renewal.
Why the swale line matters more than the lawn line
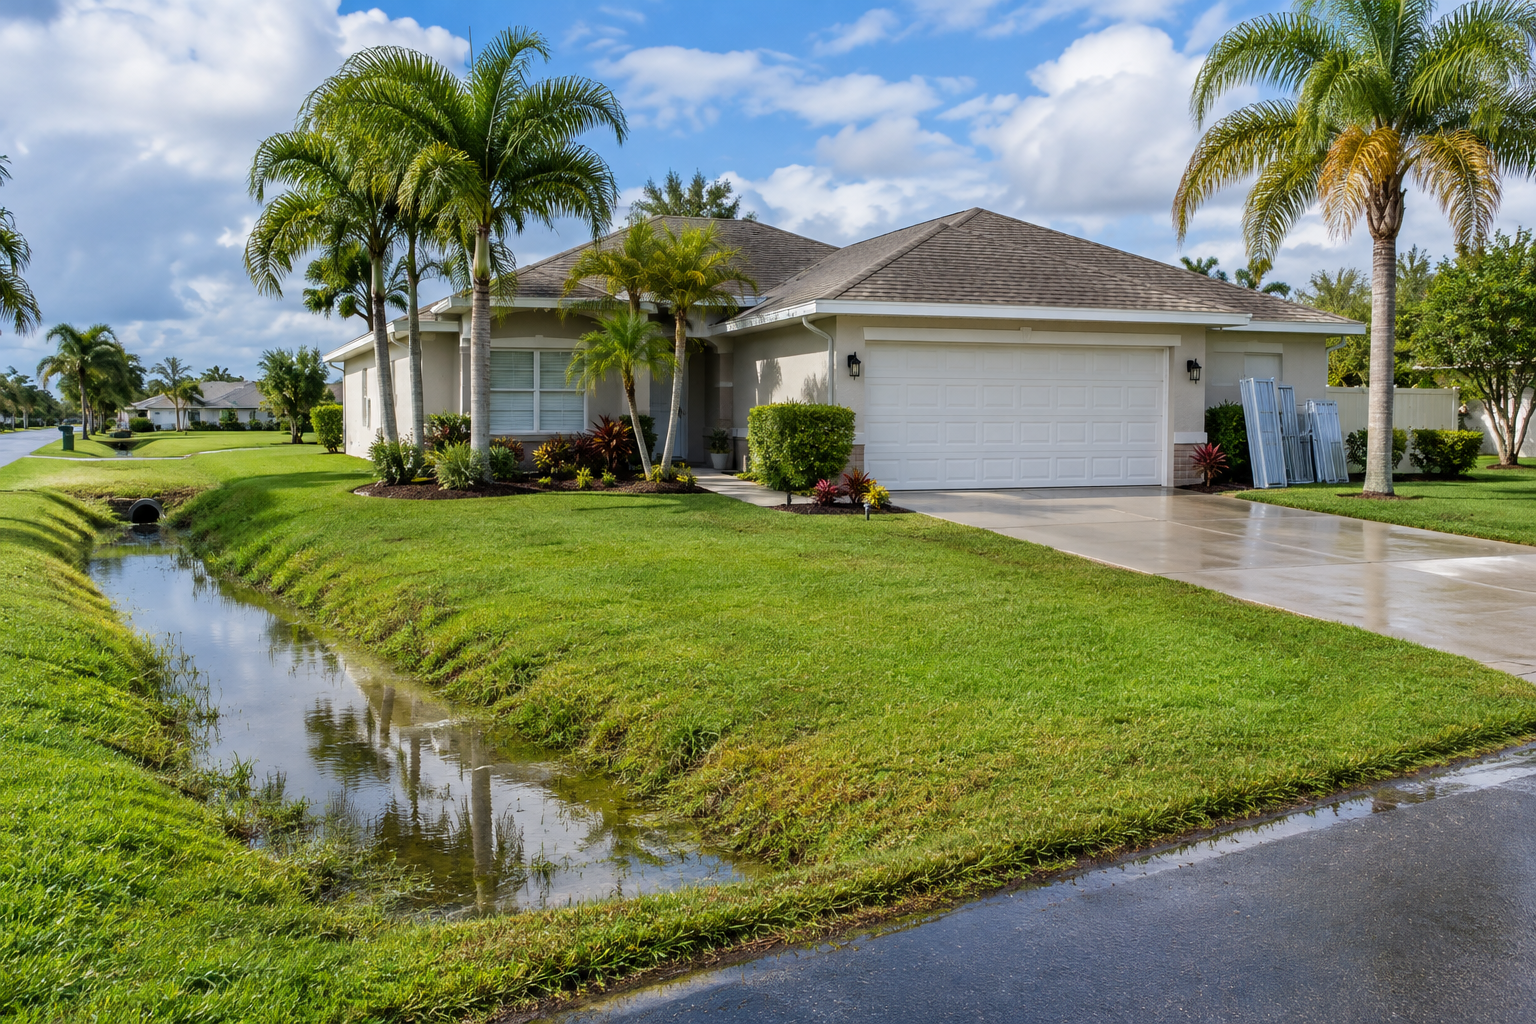
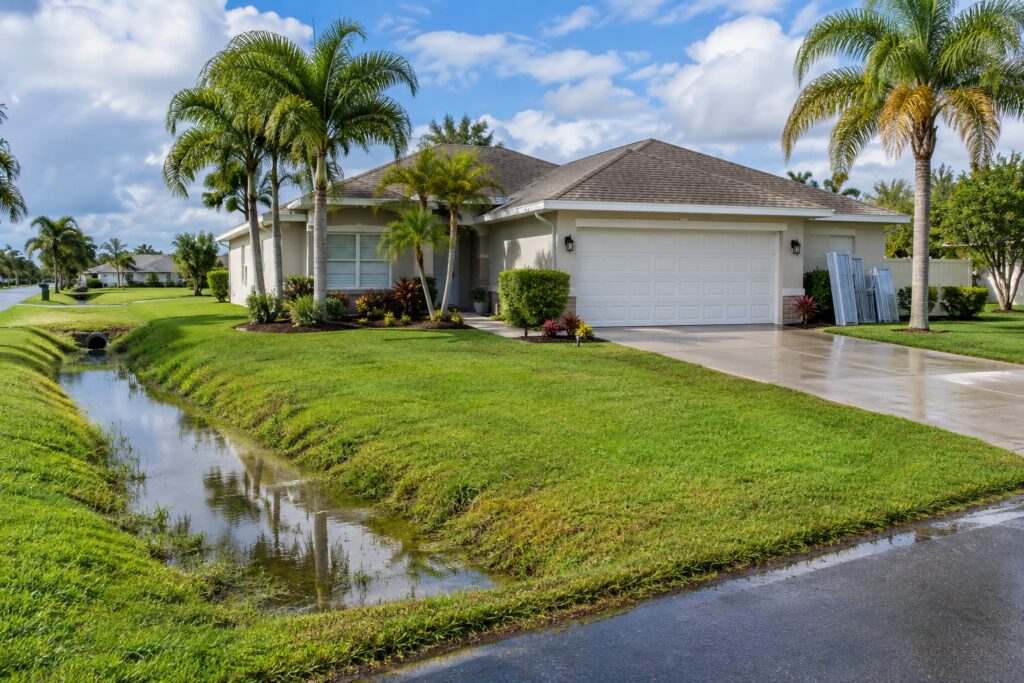
In many Indian River County mainland neighborhoods, the lot’s drainage pattern is a bigger value signal than the landscaping package. A shallow swale that carries water away from the home, a properly graded yard, and intact drainage easements can make a property far easier to live with during summer storms and king-tide influenced rain events. Buyers focused on Mainland Living should treat the swale as part of the property’s infrastructure, not just the edge of the yard, because a blocked or filled swale can send water toward the driveway, garage, or neighboring lots. The same is true for Stormwater Drainage: ask who maintains the swale, whether the county or HOA has any drainage standards, and whether recent fill dirt, French drains, or driveway extensions altered the original grade. In unincorporated areas, tax bills also deserve attention because the final bill reflects the county, school board, and any special district millages, plus the parcel’s assessed value; two homes with similar list prices can carry very different annual costs depending on location, homestead status, and whether the property sits in an HOA or a special taxing district.
How wind mitigation and flood zone data should shape your offer
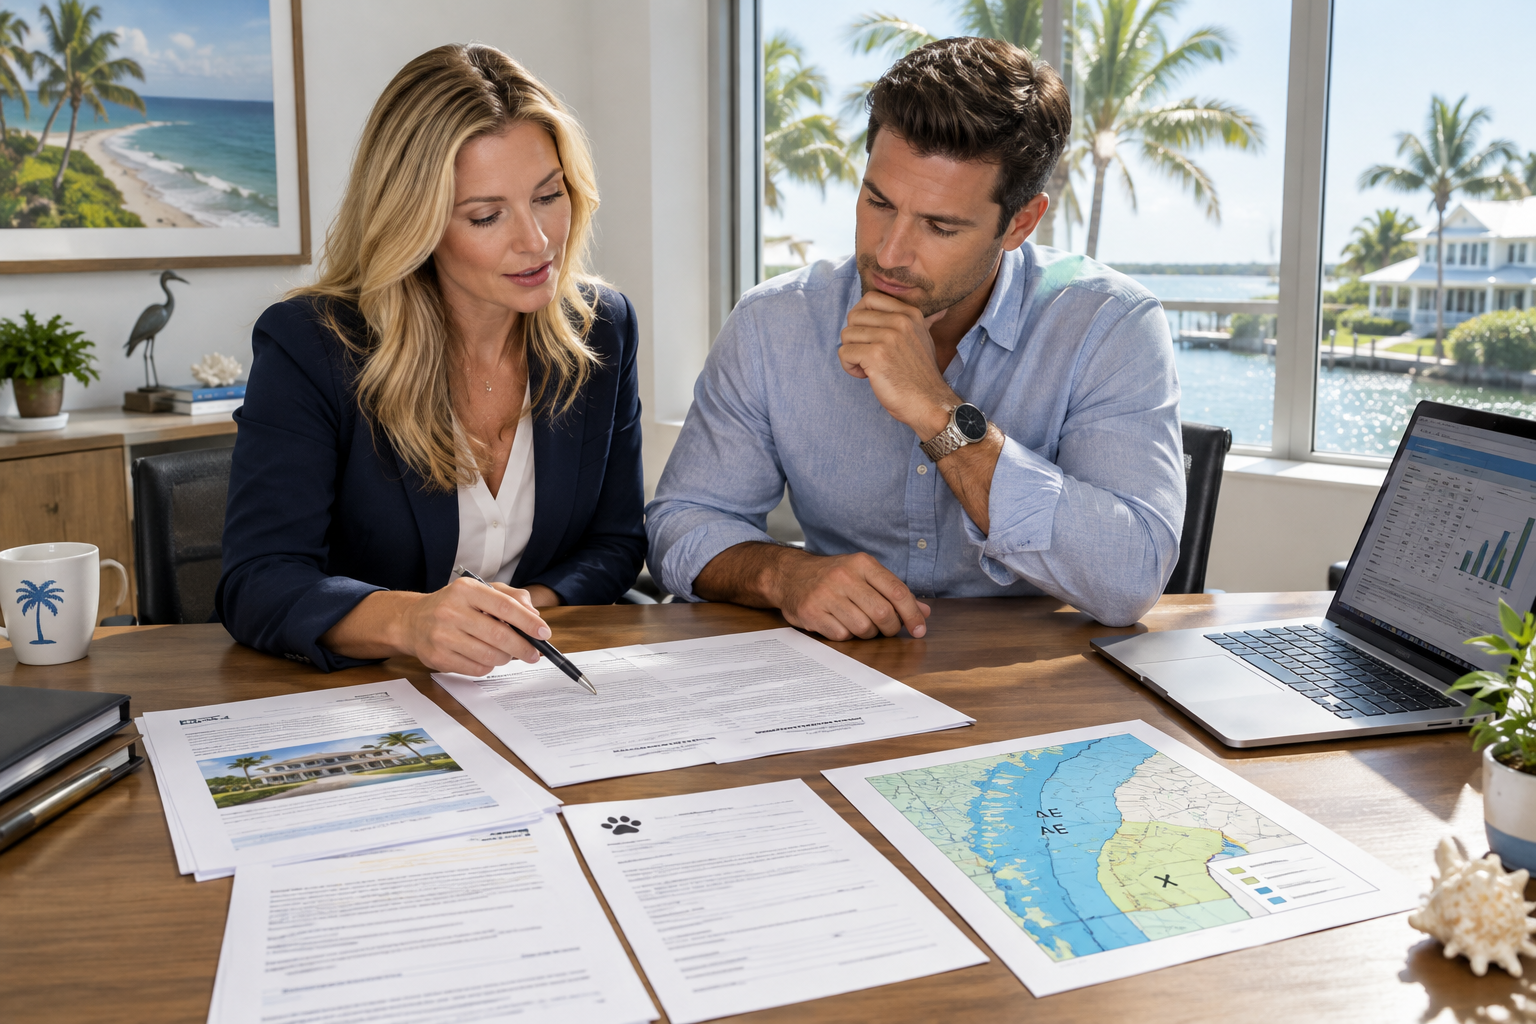
Mainland does not mean low-risk. The inland side of Indian River County still faces tropical wind, driving rain, and occasional surge-related rainfall patterns, so roof-to-foundation details matter as much as square footage. Buyers should ask for the wind mitigation inspection, the 4-point inspection, and the roof age before relying on a fast insurance quote. Hip roofs often perform better than older gable configurations, and roof deck attachment, roof-to-wall connections, secondary water barriers, and protected openings can all influence insurability and pricing. Homes built or substantially improved after modern Florida Building Code changes generally have an advantage, but every structure should be verified rather than assumed. Flood Zone X may look comforting on a map, yet it does not erase drainage concerns; Zone AE can trigger lender and insurance questions and may require an elevation certificate or additional flood review. In practice, the buyer who compares structure, elevation, and drainage together usually gets a clearer picture than the buyer who only compares the list price.
4-point due diligence checklist for mainland single-family buyers
- Confirm the exact flood designation, ask for any elevation certificate, and verify whether the home sits in Zone AE, Zone X, or a nearby transition area that could affect insurance and lending.
- Walk the lot after a rain if possible, inspect the swale, driveway crown, gutters, and any standing water, and confirm whether drainage changes would require county approval.
- Review zoning, setback rules, HOA documents, and any acreage-use restrictions if the home is in Sebastian, Fellsmere, or another non-HOA or lightly regulated pocket of the mainland.
- Request the wind mitigation report, roof age, and 4-point inspection early so you can estimate insurance accurately before you negotiate price or repairs.
Final Considerations for Vero Beach Buyers
Mainland single-family homes in Vero Beach can offer more lot size, easier access, and better value than barrier island inventory, but the strongest purchase is the one that performs well under local conditions, not just under a showing light. Drainage swales, grading, zoning, flood zone status, roof construction, and insurance readiness all affect how a home lives day to day and how it holds value over time. Buyers who verify those details before they write an offer are far better positioned to avoid costly surprises and to choose a property that fits both their lifestyle and the realities of Indian River County ownership. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.
FAQ
Are mainland homes in Flood Zone X always the safest and cheapest to insure?
No. Flood Zone X usually indicates lower mapped flood risk than AE, but it does not eliminate drainage issues, wind exposure, or insurance underwriting concerns. Roof age, elevation, previous water intrusion, and the property’s overall condition can still affect premiums and lender requirements.
Can a buyer change or fill a drainage swale on a mainland lot?
Not without checking first. Swale changes can trigger county, HOA, or easement issues, and improper grading can create runoff problems for neighboring lots. Before altering drainage, verify the parcel’s recorded drainage responsibilities and obtain any required approvals.