On Vero Beach‘s mainland, the smartest single-family purchase decisions usually come down to drainage, wind resistance, and the paper trail behind the lot, not just granite counters and curb appeal.
Why Mainland Drainage Swales Matter More Than Curb Appeal
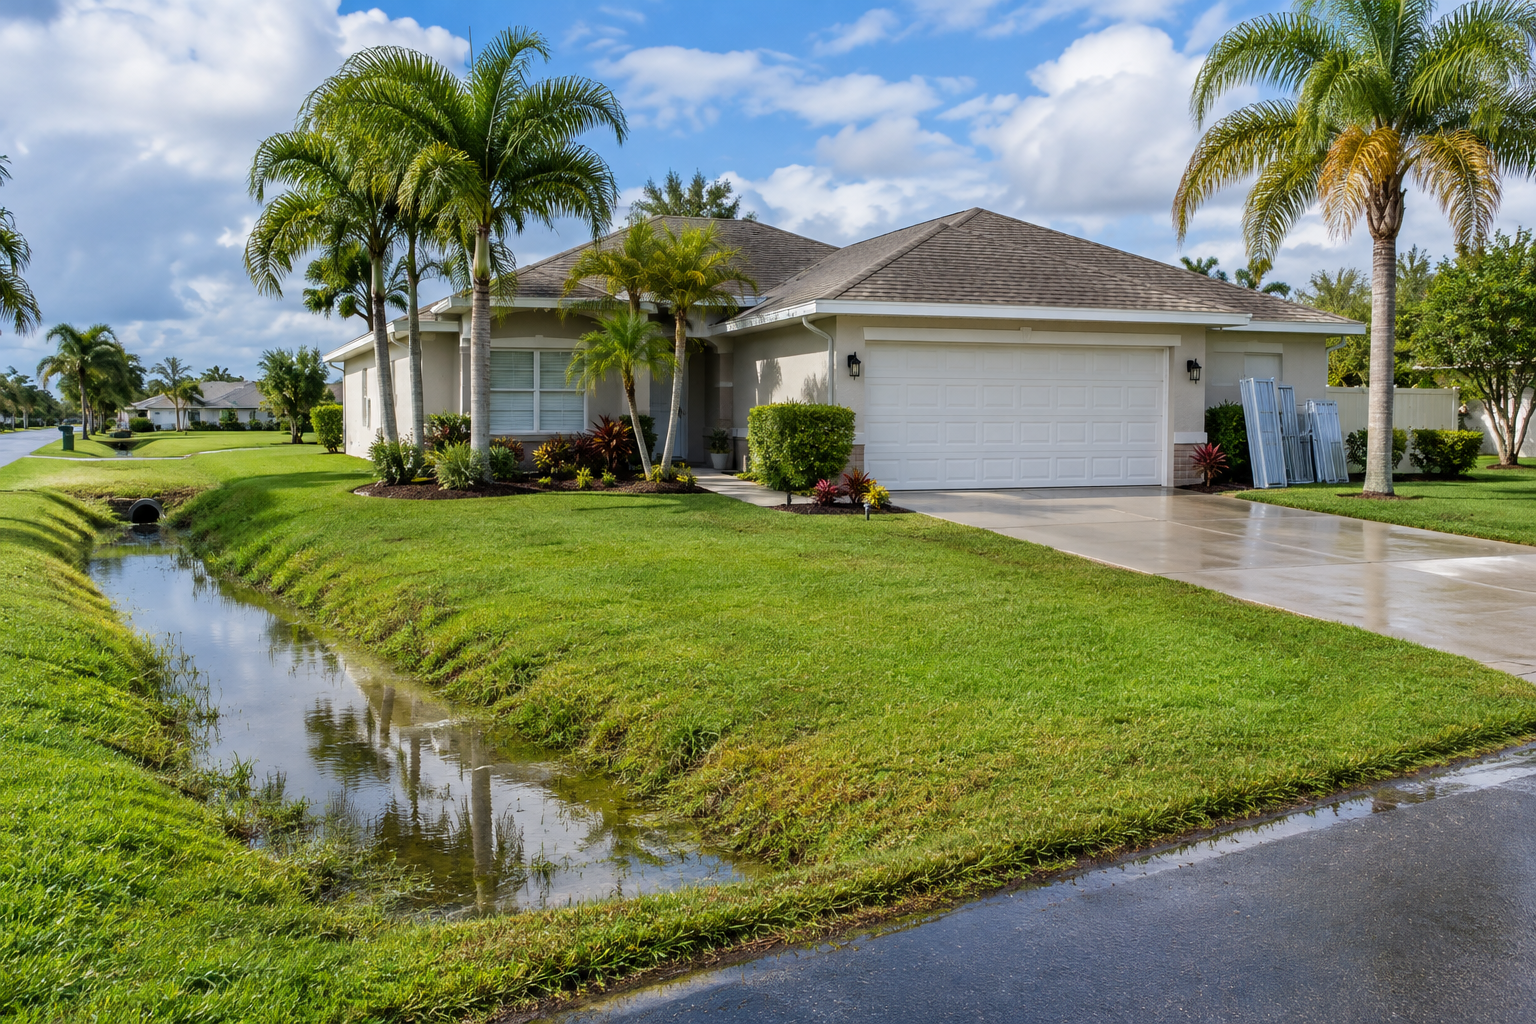
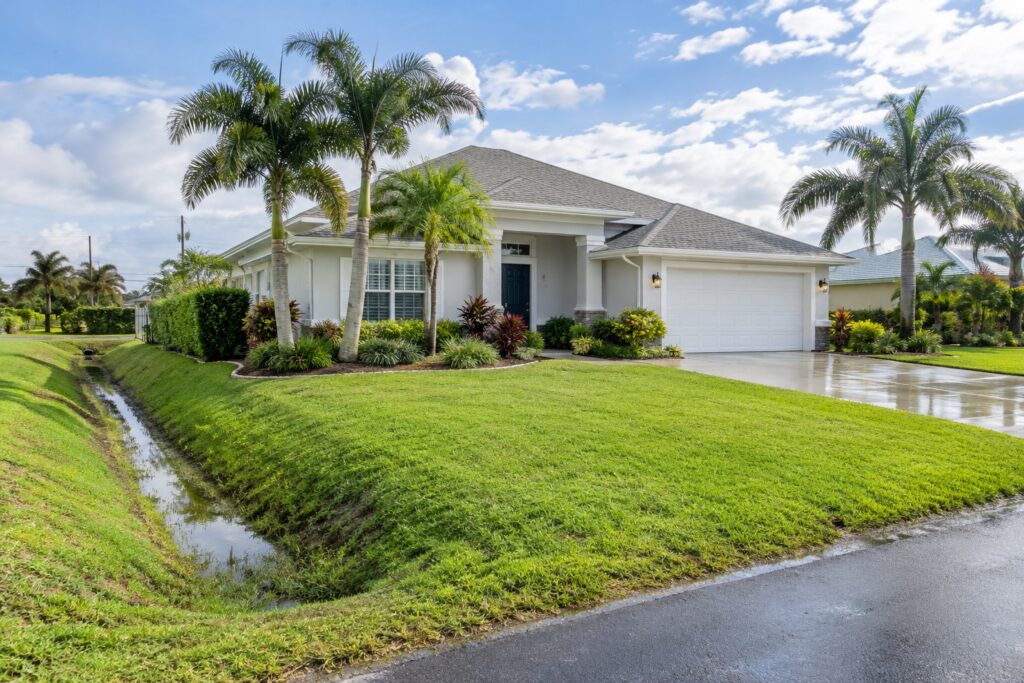
In master-planned neighborhoods along 58th Avenue and Route 60, the side yard swale is part of the property’s performance system. A swale that has been flattened by fill dirt, buried under landscape rock, or interrupted by an unpermitted patio can push stormwater toward the foundation during a summer downpour. That is why buyers should study the survey and the ground elevations before they get attached to fresh paint or a screened porch. In Mainland Living, a lot that looks perfectly dry in January can behave very differently when the afternoon storm line stalls over Indian River County.
Indian River County expects drainage patterns to work as designed, and that matters even more on non-HOA acreage in Sebastian or Fellsmere, where the owner may be managing grading and runoff without community oversight. A buyer should ask whether the lot drains to the front swale, whether there are recorded drainage easements, and whether any landscaping changes have altered the approved flow of water. If the seller cannot explain where water goes after a heavy rain, the property deserves a second look. The same is true for lots near canals, retention ponds, and low-lying edges of the Indian River Lagoon watershed, where poor grading can create long-term maintenance issues.
What a Wind-Mitigation File Should Show on a Mainland Roof
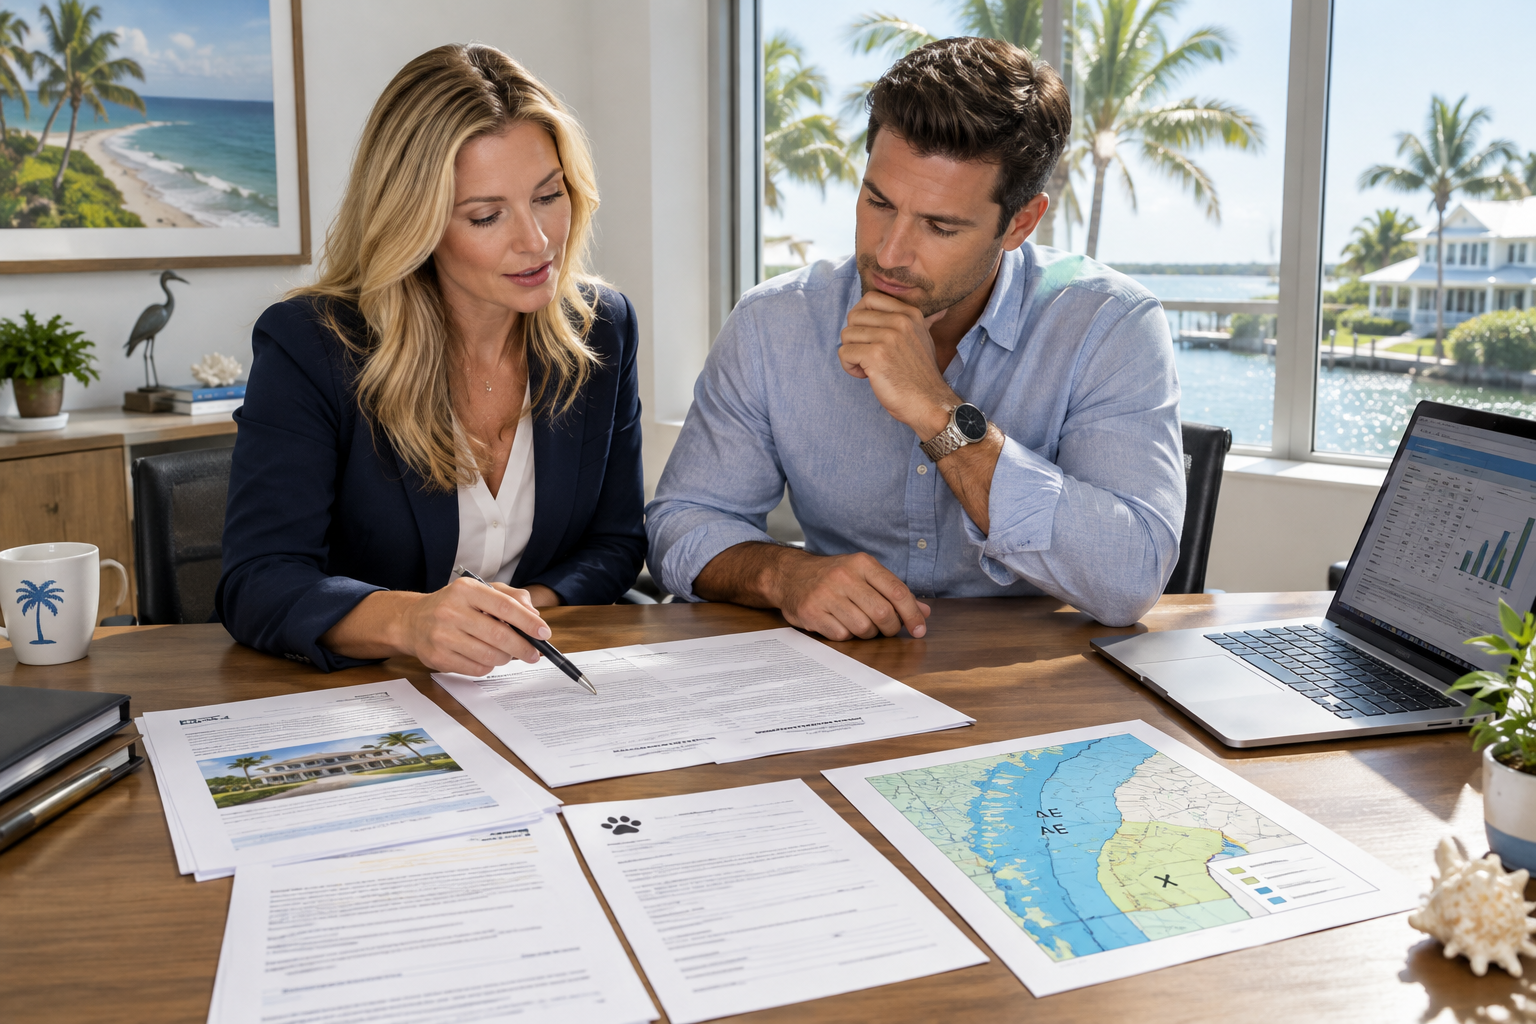
Outside the barrier island, roof-to-foundation performance still drives insurance and resale value. A strong file should show the roof permit history, roof age, roof deck attachment, roof-to-wall connectors, opening protection, and any secondary water-resistance features. Buyers comparing two similar homes should not treat this as a minor paperwork item; a documented wind mitigation package can materially affect premiums and lender comfort. When a home has updated straps, clips, shutters, and a newer roof assembly, the market often values it more favorably than an older house with no proof of reinforcement, even if the exterior finishes look comparable. That is especially important when shopping Wind Mitigation details on a house in Flood Zone X, because lower flood exposure does not cancel wind exposure, and a house in AE may need both flood documentation and a stronger insurance file.
Buyers should also remember that structural upgrades are not just for storm season. In Indian River County, a clean permit record and visible code compliance can make the appraisal and inspection process smoother, particularly if the home has changed hands several times or includes additions such as a lanai enclosure, detached workshop, or widened driveway. If those improvements were completed without permits, the buyer may inherit correction costs, insurance complications, or title delays.
Four Items to Confirm Before You Write the Offer
- Survey and grading: Review the survey for swales, drainage easements, setbacks, and any signs that fill, hardscape, or landscaping has altered the lot’s approved drainage pattern.
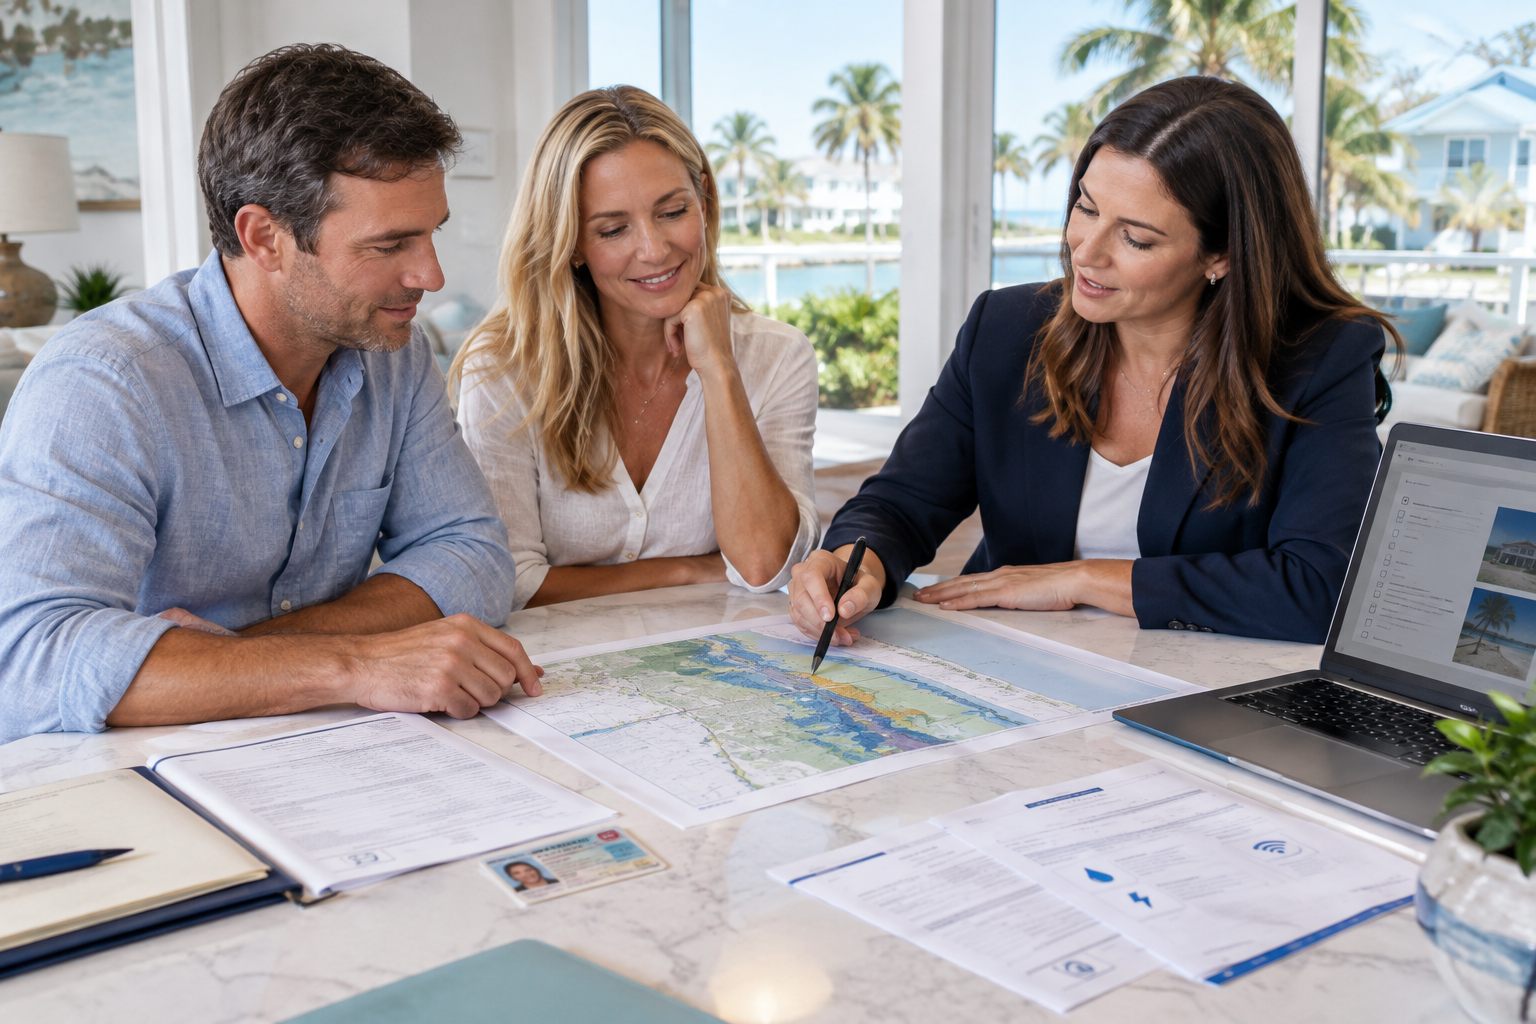
- Insurance and flood profile: Confirm whether the home is in AE or X, request an elevation certificate if available, and get a quote before waiving contingencies.
- Permit and mitigation history: Ask for roof records, wind mitigation reports, four-point inspection results, and permits for any additions, enclosures, or structural changes.
- Zoning and association rules: If the property is in Sebastian, Fellsmere, or a mainland HOA community, verify setbacks, use restrictions, special assessments, and any rules that affect fences, sheds, or driveway expansion.
Final Considerations for Vero Beach Buyers
Mainland single-family homes can deliver strong value compared with barrier island pricing, but only when the buyer prices in drainage, wind resistance, and zoning from the start. A property with a clean swale, a documented roof system, and a clear permit trail is usually the safer long-term hold than a prettier house with hidden grading issues or incomplete records, especially in a market shaped by summer storms, flood mapping, and county code enforcement.
FAQ
Is Flood Zone X always a better buy than AE on the mainland?
Not automatically. Zone X often means a lower mapped flood risk, but drainage problems, poor grading, and wind exposure can still create expense. Buyers should still review the site survey, ask about past water intrusion, and price insurance before closing.
Do acreage homes in Sebastian or Fellsmere have fewer rules?
They usually have fewer HOA restrictions if they are not in an association, but county zoning, setbacks, drainage requirements, septic or well considerations, and permit rules still apply. Fewer association rules does not mean fewer due-diligence steps.
For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.