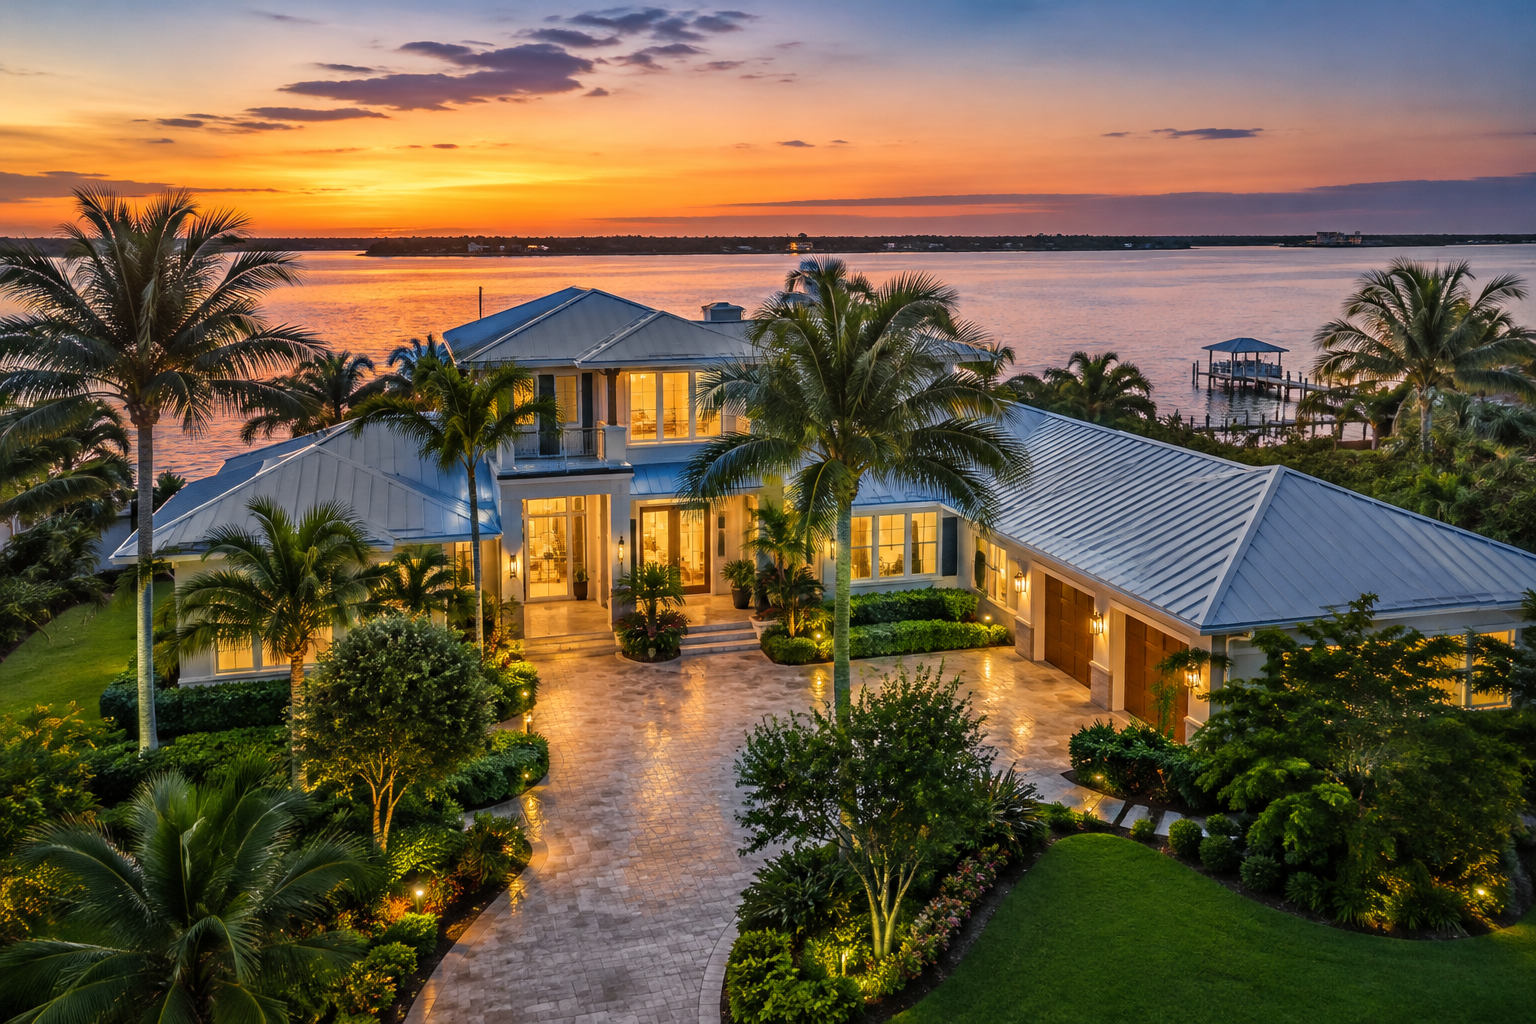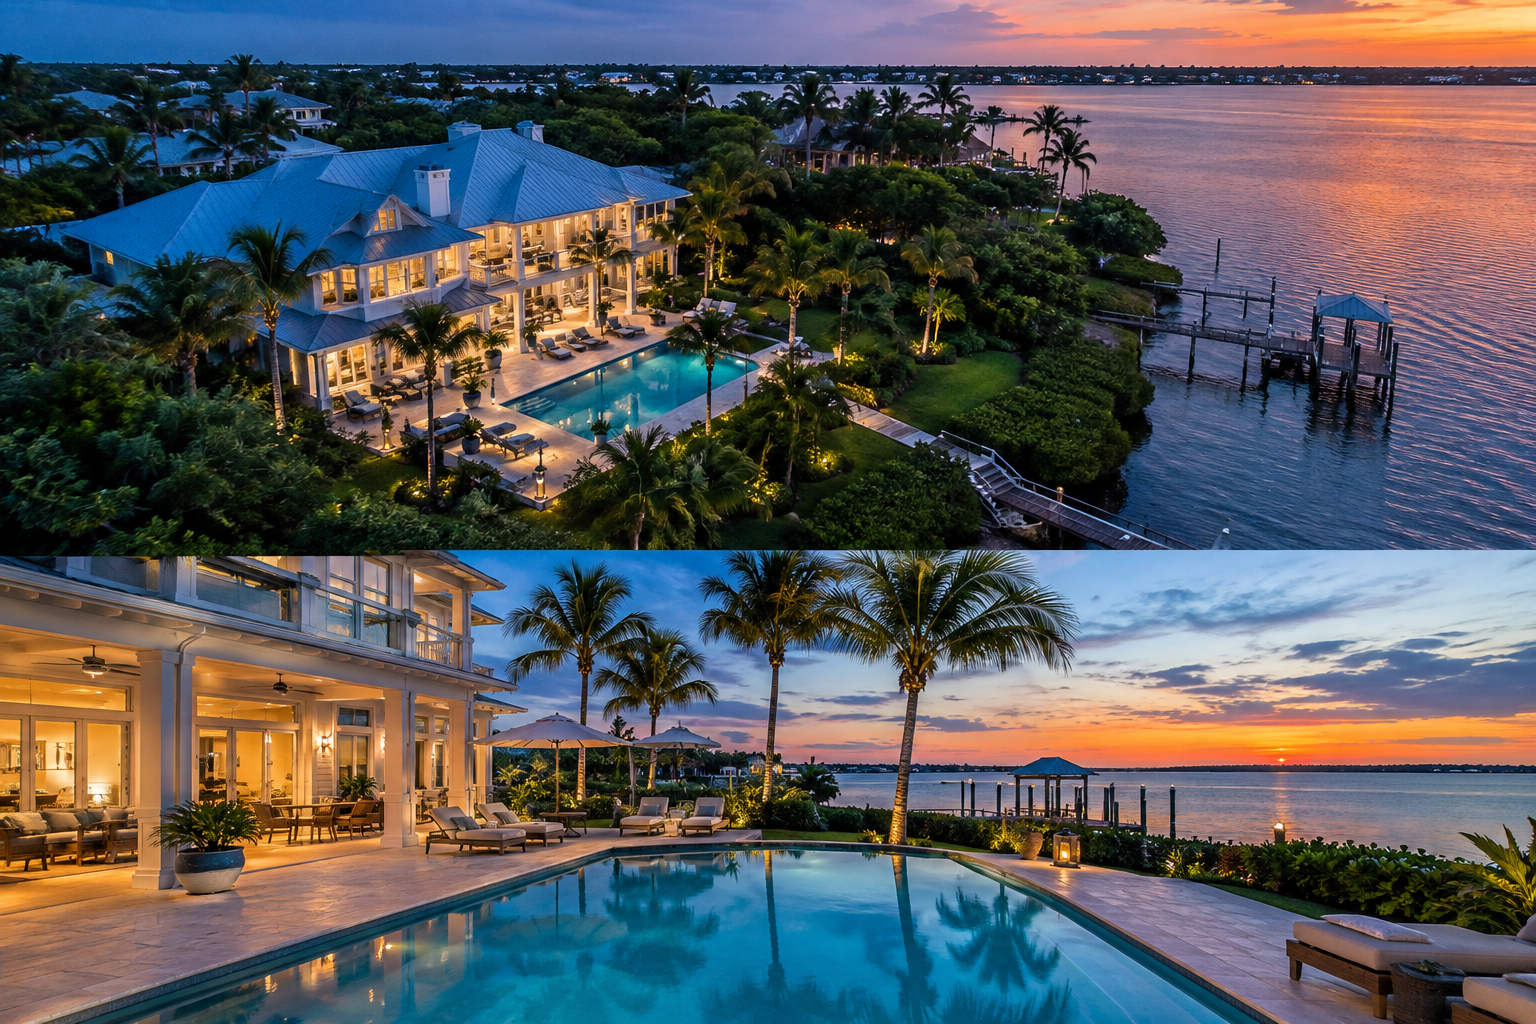
In Vero Beach, a home on the barrier island and a home on the mainland can look similar on paper while sitting in very different pricing universes once flood insurance, roof age, and wind protection are placed under the microscope. Sellers in 32963 who ignore that gap often overprice by borrowing from the wrong pool of buyers, while mainland sellers sometimes leave money on the table by failing to show how a strong insurance profile supports a firmer ask.
Price the insurance profile before you price the square footage
The fastest way to lose credibility with buyers in Indian River County is to blend AE-zone waterfront risk with X-zone inland convenience and call it a true comp set. A 2,200-square-foot home east of the river with a newer roof, documented opening protection, and lower carrying costs may outperform a larger 32963 property that needs roof replacement or has a thinner wind mitigation record. That is why pricing should start with the operating-cost story, not just the sales price history. Buyers arriving from the Northeast are used to comparing tax bills, insurance quotes, and hurricane-readiness long before they compare backsplash finishes. If your listing can prove value through permits, 4-point inspection details, and a clean roof timeline, you can justify a tighter number without making the home look overpriced.
Use Pricing Strategy and Home Selling Strategies to frame your launch price around the actual buyer math rather than an inflated neighborhood average.
Front-load disclosures so buyers can move from showing to offer
Pre-market transparency matters even more along the Atlantic coastal barrier island, where buyers are alert to wind load, corrosion, and the age of critical systems. Florida sellers should be ready to discuss roof permits, wind mitigation reports, repair receipts, insurance claim history, and any known conditions that could surface during inspection. In condominium communities and many HOA neighborhoods, milestone inspections, reserve conversations, and assessment risk now influence offer strength just as much as finishes do. If a board has issued an update or the association is still collecting information tied to building safety, buyers will discount uncertainty immediately. A clean disclosure package does not eliminate negotiation; it simply keeps the first round of negotiations focused on real facts instead of avoidable fear.
That approach is especially important when the listing is aimed at the winter buyer pool. Seasonal Northeast migration peaks tend to bring more qualified showings, but those buyers often want quick answers. When they can verify roof age, wind credits, and association status on the front end, they are more likely to move from showing to offer before the market cools again in spring. In multiple-offer situations, the seller who has already organized the documentation can use deadline control, proof of funds, appraisal-gap language, and repair-credit caps to protect the net without losing momentum.
4-point pre-listing checklist for Indian River County sellers
- Confirm the flood zone and insurance story: know whether the property is in AE or X, and understand how that changes buyer expectations.
- Gather roof and wind mitigation records: permits, inspection reports, and upgrade receipts should be ready before photos are taken.
- Review HOA or condo risk items: milestone inspections, reserve status, and any pending assessments must be understood before launch.
- Set a pricing review date: if showings are strong but offers lag, revisit the strategy within 10 to 14 days while momentum is still on your side.
Final Considerations for Vero Beach Buyers
Vero Beach sellers get better results when the asking price reflects the true cost of ownership, the real strength of the property’s documentation, and the market segment most likely to buy it. In this market, square footage alone does not tell the story; flood zone, roof condition, wind mitigation, association health, and seasonal demand all shape the number buyers are willing to write down. The smartest listings on the barrier island and mainland are launched with precise comps, clean disclosures, and a negotiation plan that anticipates the questions coastal buyers will ask before they ever step through the door.
FAQ
How do I price a Vero Beach home when nearby sales include both mainland and 32963 properties?
Use only the most relevant comps first, then make explicit adjustments for flood zone, roof age, insurance costs, and coastal exposure. A mainland sale and a barrier island sale may be close in square footage but far apart in buyer expectations and carrying costs.
Who can help me price and negotiate a Vero Beach coastal listing?
For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.