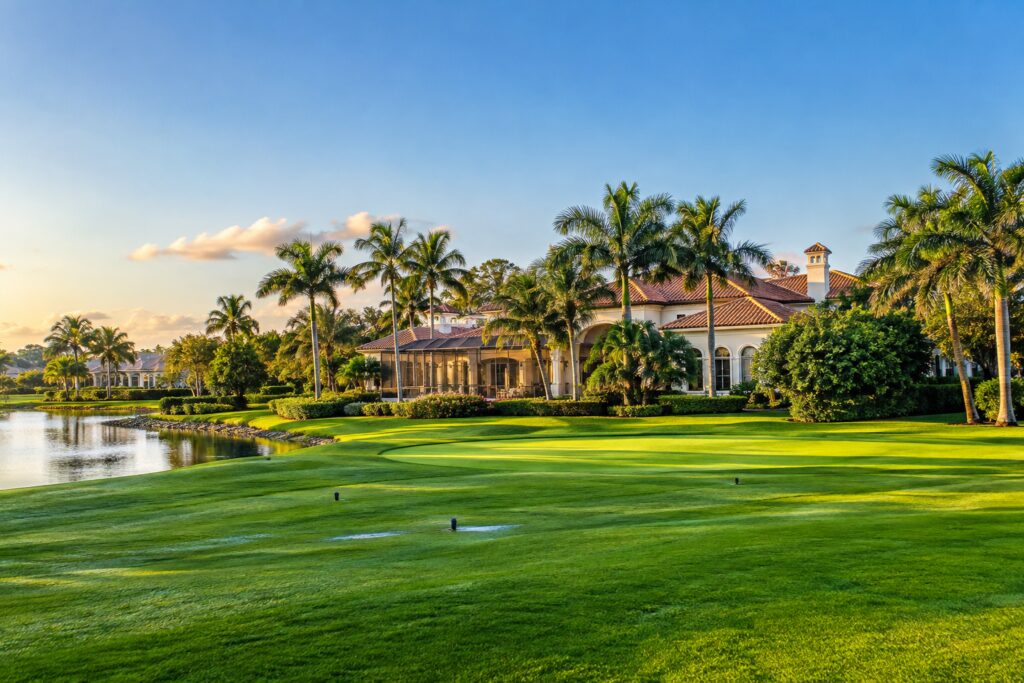
A Vero Beach fairway home can look simple from the tee box and still carry a layered ownership cost that only shows up in the documents: club equity or non-equity status, transfer fees, setback limits, irrigation responsibilities, and the real-world exposure of living beside an active course in Florida’s salt-air climate. In Indian River County, that matters because a home near the fairway is never just about the view; it is about how the club is financed, how the lot drains in summer rain, and whether the property sits in an AE or X flood zone if the community is also shaped by coastal insurance rules and barrier-island demand.
Membership Structure Comes Before the View
Before a buyer falls in love with a screened lanai facing the 18th fairway, the first question should be whether the club is equity or non-equity and whether membership is mandatory, optional, or tied to a specific home class. Equity clubs usually give members an ownership interest in the club entity or a governance voice, while non-equity clubs generally operate more like a long-term service agreement with the club retaining control of capital decisions. That distinction affects dues stability, assessment risk, resale timing, and whether a buyer can exit a membership cleanly when the property sells. If the listing sits inside a gated community, the buyer should read the governing package as carefully as the sales brochure. Golf Communities often carry separate operating budgets, reserve obligations, and clubhouse assessments, while Country Club Real Estate can include mandatory dues that survive resale even when club access is limited to certain membership classes.
In Vero Beach, transfer policies deserve the same scrutiny as monthly dues. Some clubs require a new owner to pay an initiation fee at closing, even if the seller paid one years earlier, while others allow a transfer credit, a reduced fee, or a waiting period before full privileges begin. Mandatory golf memberships may also include cart fees, food-and-beverage minimums, capital contribution charges, locker fees, and tennis or social-tier limitations that are not obvious from a drive-by showing. The practical question is not just whether the buyer wants to play golf; it is whether the membership structure matches the household’s actual use pattern, seasonal occupancy, and willingness to carry club costs through slower resale periods.
Setbacks, Errant Balls, and the Drainage System Under the Fairway
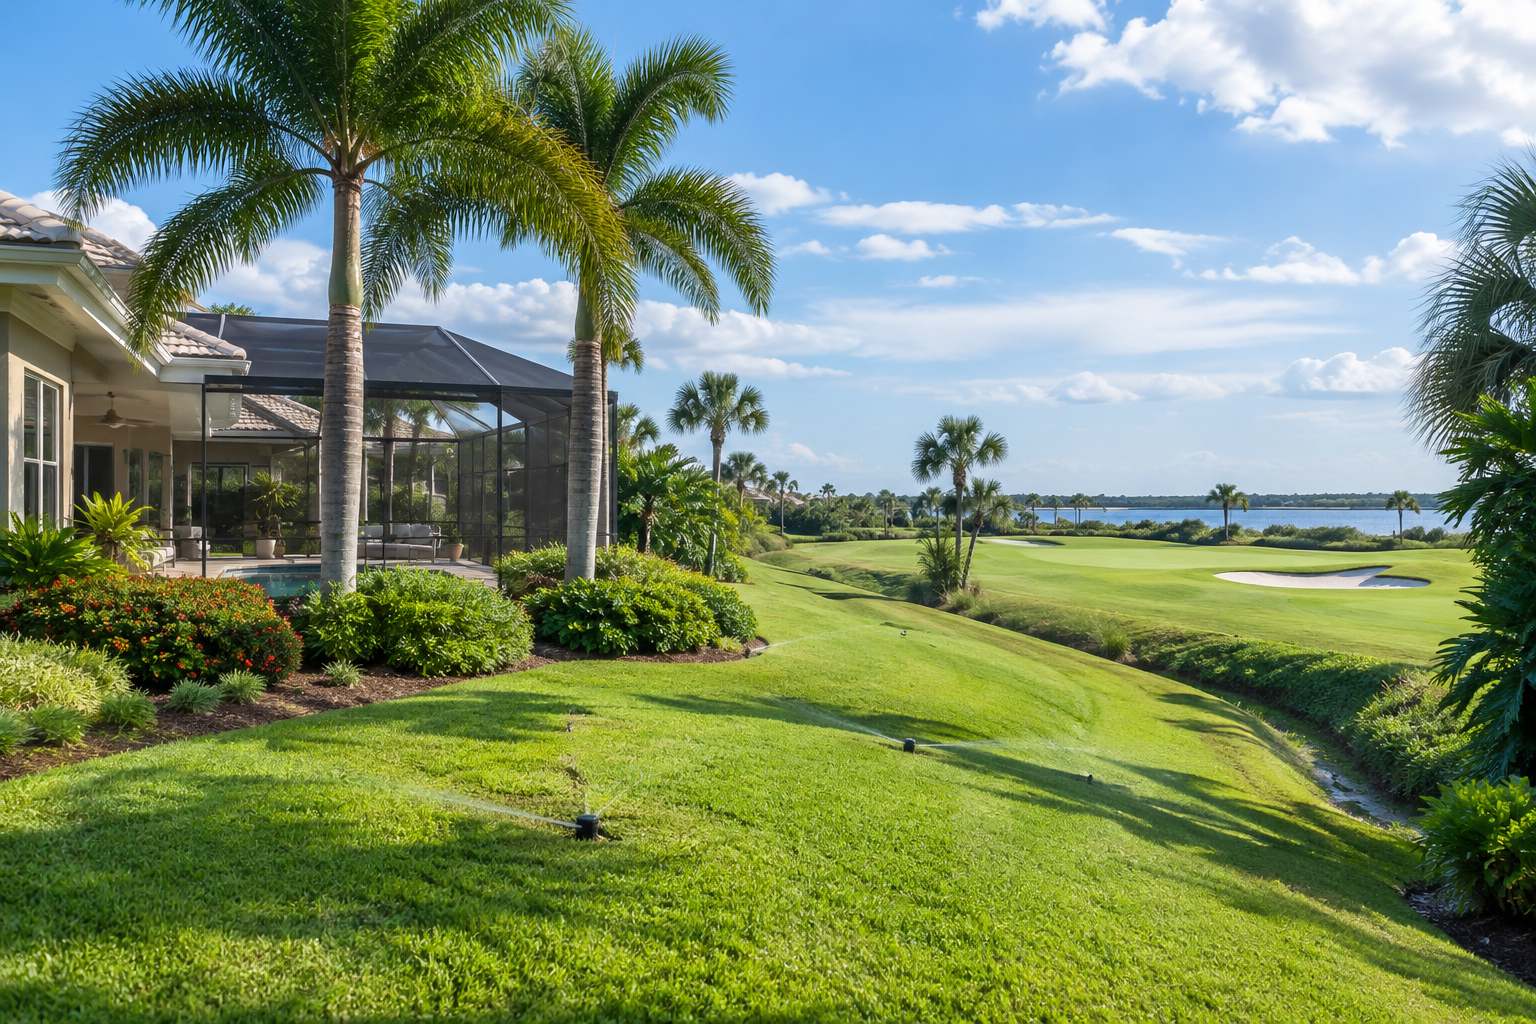
Course-front homes in Indian River County can feel private until a summer storm, a maintenance outage, or an errant tee shot exposes how thin the buffer really is. Setback lines, landscape berms, netting, and cart-path placement are not decorative details; they are the first layer of protection against impact damage and privacy loss. Buyers should ask whether the lot boundary, the building envelope, and the patio enclosure are set far enough back from the playing corridor to reduce routine ball strikes, especially on holes with doglegs or elevated tees. Florida communities do not guarantee golf-ball-free living, so the key question is how the documents allocate risk, whether the HOA or club acknowledges recurring impact zones, and whether prior owners have reported repeated damage. In a market where a home can sit high on value and still be vulnerable to a hard slice, the practical buffer matters more than the postcard view.
The maintenance system beneath the grass matters just as much. Fairway neighborhoods often rely on a master association irrigation network, lake-fed pumping, drainage swales, and coordinated stormwater retention areas that serve both the homes and the course itself. If the club controls the pumps but the HOA helps fund the lakes, the buyer needs to know who repairs a broken line, who pays for turf loss after a pump failure, and whether special assessments can be levied when the irrigation or drainage system needs replacement. In storm seasons, the difference between an AE flood zone and an X zone can affect insurance and lender comfort, but even homes outside the mapped floodplain can suffer standing water if the private fairway system is undersized or poorly maintained. In Vero Beach, that is not theoretical; heavy rain, high groundwater, and older master-planned drainage systems can turn a manicured view into an expensive liability if the association documents are vague or the reserves are thin.
Four-Distance Due Diligence Checks Before You Write the Offer
- Pull the full club and HOA packet. Read the declaration, rules, membership addendum, resale certificate, estoppel, and any amendment that governs initiation fees, transfer rights, and assessment authority.
- Confirm the exact membership tier. Verify whether the property includes equity, non-equity, golf, sport, or social privileges, and ask whether the owner must maintain a specific membership class to keep access to the amenities.
- Review the survey, drainage, and flood data. Compare setback lines, easements, and elevation information against the home’s actual placement and ask whether the lot is in AE or X, especially if the home backs to a lake, swale, or low fairway edge.
- Investigate assessments and maintenance history. Ask about recent or pending reserve studies, stormwater repairs, irrigation upgrades, clubhouse capital projects, and, for villa or condo-style homes, any milestone inspection findings or structural special assessments.
Final Considerations for Vero Beach Buyers
Fairway living in Vero Beach works best for buyers who treat the club as part of the property, not as an amenity afterthought. The right home can deliver strong lifestyle value, but only if the membership rules, transfer costs, setback realities, irrigation obligations, and flood exposure are understood before closing. In Indian River County, the best purchase is the one that still makes sense after the first invoice, the first summer storm, and the first resale conversation.
FAQ
How do I know whether a Vero Beach club home has mandatory membership?
Start with the recorded governing documents and the seller’s disclosure, then confirm whether the membership is attached to the lot, the home, or only the current owner’s account. In many club communities, the answer is not visible from the listing remarks and must be verified through the estoppel, the declaration, and the club’s own transfer rules.
Who is responsible for golf ball damage or fairway drainage issues?
Responsibility depends on the governing documents, the location of the damage, and whether the issue involves routine play, a maintenance failure, or a documented association defect. Buyers should never assume the club will cover property damage or drainage problems without written support in the documents. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.