In Vero Beach, the spread between a high-performing rental and a mediocre one is often decided by three items that rarely show up in a glossy listing: corrosion, insurance, and turnover timing. On the barrier island in 32963, salt air accelerates exterior wear; on the mainland, flood zone and stormwater exposure can still reshape reserves; and for investors using a 1031, lease expirations have to line up with replacement-property closing windows. That is why small multifamily owners in Indian River County should underwrite each acquisition as a sequence of maintenance cycles, tax deadlines, and compliance checkpoints, not just as a cap-rate number.
Underwriting a Multifamily Deal Around Coastal Replacement Cycles
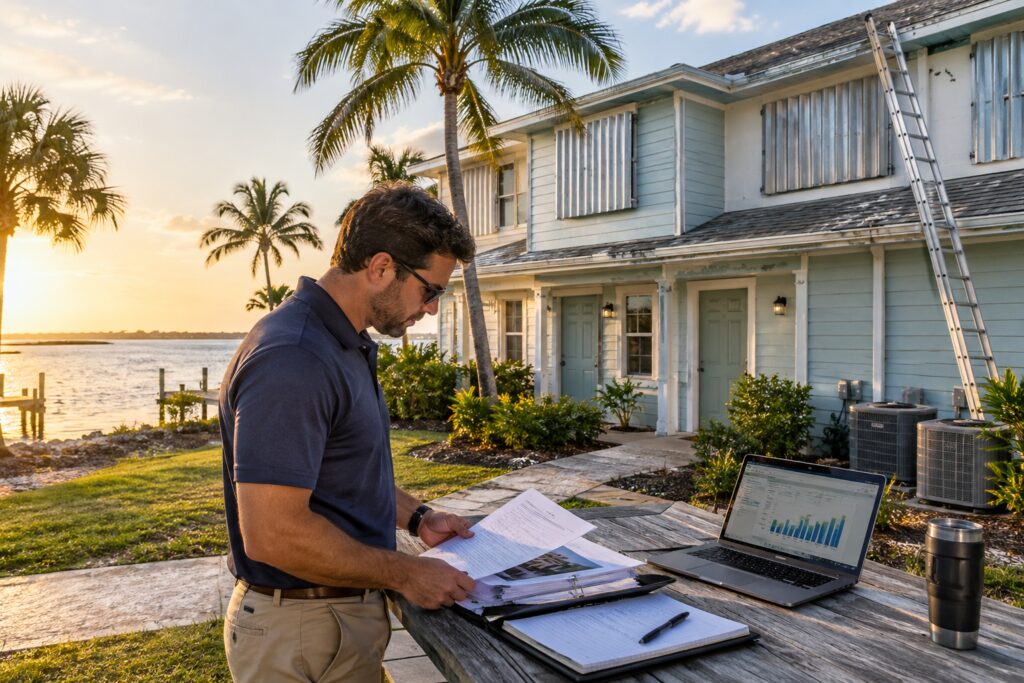
When comparing duplexes, triplexes, or small apartment buildings, start with gross scheduled rent, economic vacancy, and the operating expense ratio, then layer in a reserve schedule that reflects local wear patterns. A roof that might last longer inland can need a shorter planning horizon near the Indian River Lagoon or the Atlantic barrier island, and the same logic applies to exterior paint, balcony hardware, window seals, and HVAC condensers. If the property sits in AE flood zone, your analysis should include flood insurance, elevation-related mitigation, and the possibility of higher out-of-pocket restoration costs after a storm. If it sits in X zone, do not assume the maintenance burden disappears; it only shifts toward wind exposure, humidity, and salt corrosion. For owners prioritizing 1031 Exchange readiness, the question is not only whether the asset cash flows today, but whether it can survive the holding period without an unplanned capital event that disrupts financing or tax-deferred exchange timing.
- Use a per-unit reserve target that reflects location: barrier island assets usually need more aggressive exterior and mechanical reserves than comparable mainland buildings.
- Model insurance deductibles as a real operating expense, not a rare event, because one named storm can reset the math.
- Track deferred maintenance by component, not by building, so a small roof issue does not hide larger corrosion or drainage problems.
- Verify whether HOA or condo rules, reserve studies, or special assessments change the true cost of ownership before you commit capital.
Vendor Coordination and Compliance for Small Portfolios
Vendor coordination is where many otherwise sound rentals leak margin. Salt-air markets reward owners who schedule roof, gutter, paint, AC, pest, and exterior cleaning service on a fixed calendar instead of waiting for visible failure. Keep written scopes, certificates of insurance, lien releases, and before-and-after photos for every job, especially when work happens between tenant move-out and move-in. If you are managing property for others in Florida, remember that Property Management Compliance is not optional; compensation-based management generally requires the proper real estate license structure, while owners managing their own holdings still need to follow fair housing rules, trust-account practices where applicable, and local lease disclosure standards. Vero Beach landlords who want a repeatable system for Landlord Resources should also build a tenant placement process that screens income, rental references, eviction history, and credit in a consistent, compliant way. On the ground, that means coordinating with licensed contractors who can respond quickly before a tropical weather system, keeping a hurricane-readiness vendor list, and checking every new acquisition for lease caps, minimum lease terms, rental registration rules, and any association restrictions that could limit future income. If the building is a condo or part of a mixed-use association, request milestone inspection reports, structural reserve information, and meeting minutes before closing so an upcoming assessment does not erase projected cash flow.
Four-Part Due Diligence Checklist for Indian River County Investors
- Map the flood and insurance profile: Confirm whether the property is in AE or X, then compare premium estimates, deductibles, and mitigation credits before you write the offer.
- Price the salt-air reserve schedule: Ask for roof age, HVAC replacement dates, exterior coating history, balcony and railing materials, and any corrosion-related repairs from the past five years.
- Audit the lease and compliance file: Review current leases, application standards, notice provisions, HOA or condo rules, and any local registration or licensing obligations tied to the property type.
- Stress-test the exit plan: If you plan to refinance, hold, or use a 1031 exchange later, make sure the asset can support lender underwriting and a clean ownership transition without surprise capital costs.
Final Considerations for Vero Beach Buyers
Vero Beach rentals can produce stable income, but only when the acquisition is priced with coastal realities in mind. The best deals in Indian River County usually look disciplined rather than flashy: realistic reserve assumptions, documented vendor systems, compliant tenant placement, and a clear plan for insurance, flood exposure, and association oversight. Buyers who treat maintenance, tax strategy, and legal compliance as one connected investment model are in a much better position to protect cash flow on both the mainland and the barrier island. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.
Frequently Asked Questions
How does a 1031 exchange work when buying a Vero Beach rental?
A 1031 exchange lets an investor defer capital gains taxes by selling one investment property and acquiring another qualifying replacement property within strict timelines. In Vero Beach, the challenge is not only finding the right asset, but closing fast enough and documenting the transaction correctly while avoiding a deal that carries hidden coastal repair costs or association risks.
What should buyers look for in a coastal maintenance reserve?
Buyers should review roof age, HVAC condition, exterior coatings, corrosion points, flood exposure, insurance deductibles, and any HOA or condo reserve obligations. On the coast, the reserve should be sized for real replacement cycles, not generic national averages, because salt air and storm exposure shorten the life of many building components. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.