A modest purchase-price bump can matter more in Vero Beach than many mainland borrowers realize: once a home tips from conforming into jumbo territory, the monthly payment, reserve requirements, and appraisal scrutiny can change in one step, and that step is especially visible on the 32963 barrier island where insurance, flood elevation, and HOA or condo costs already stretch buying power.
The Conforming Ceiling Bites Hardest Where Coastal Costs Are Already High
Indian River County buyers often focus on list price, but lenders underwrite the loan amount, not the asking price. That distinction matters when a property sits just above the current conforming ceiling, because a slightly larger down payment, a seller credit, or a negotiated price reduction can keep the file inside conventional guidelines. Once the loan amount crosses the line, Jumbo Loans and Mortgage Rates can diverge quickly: the note rate may rise, the cash reserves test may tighten, and the underwriter may require a stronger profile for the same home.
On the barrier island, those differences compound the coastal carrying costs that many buyers underestimate:
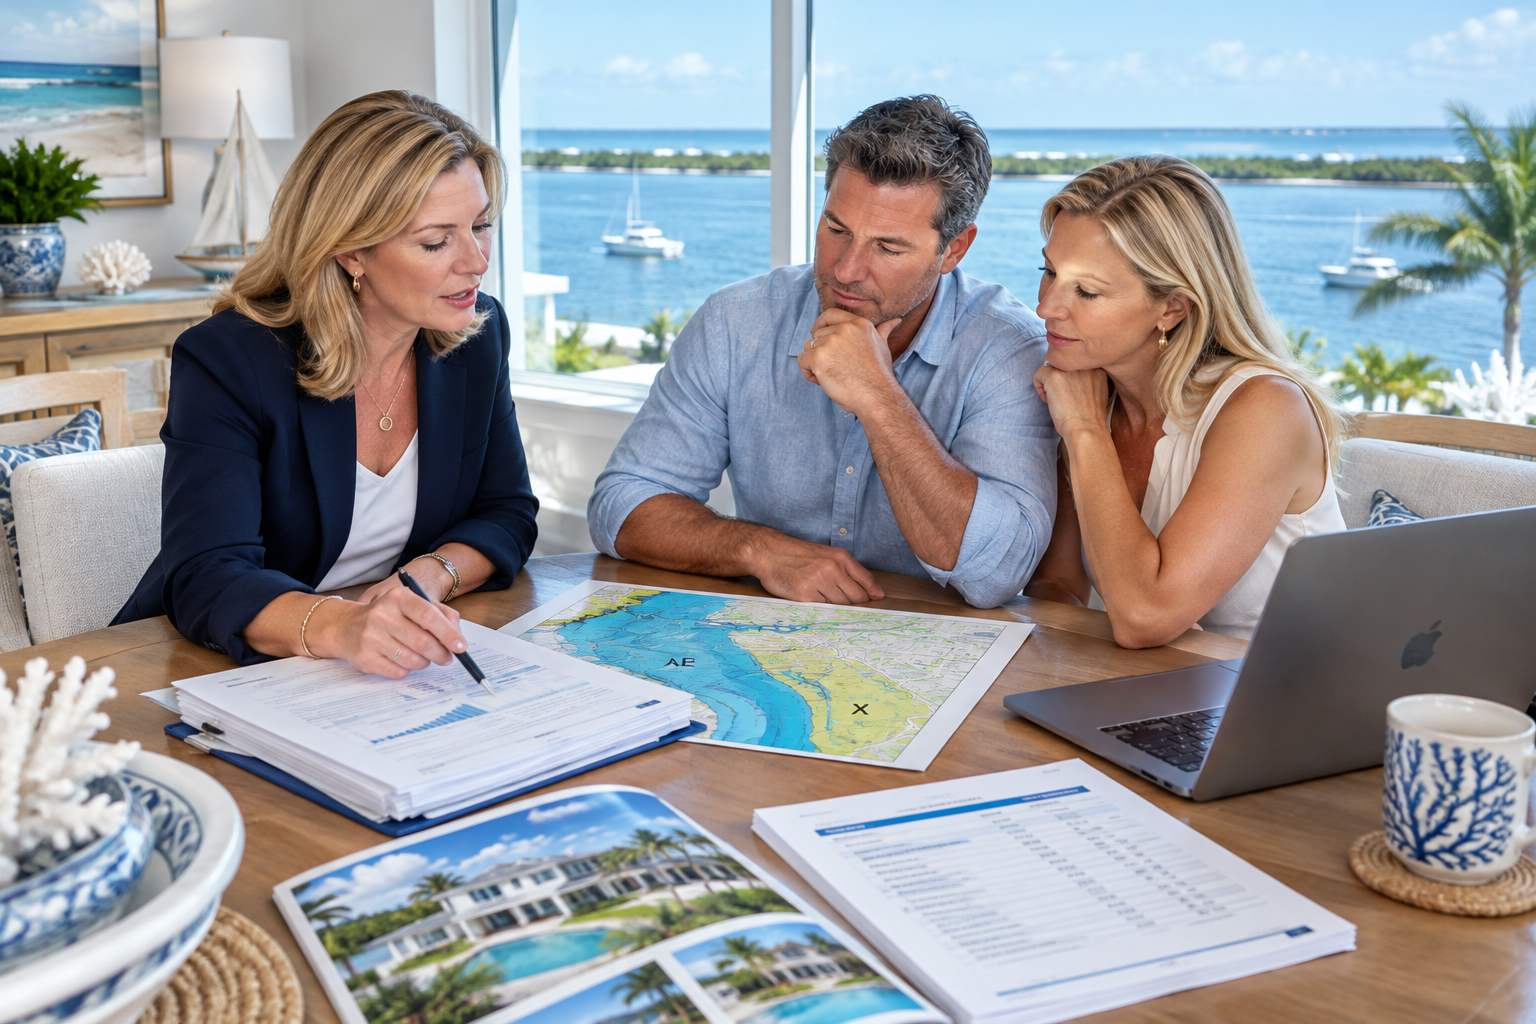
- AE flood-zone homes usually need flood insurance layered on top of wind and homeowners coverage, which raises the debt-to-income ratio even when the principal and interest payment looks manageable.
- X-zone properties can still carry meaningful premium costs if the home is older, elevated differently, or exposed to wind and roof-replacement risk.
- Condo purchases can add monthly association dues, reserve contributions, and special-assessment exposure that lenders count in full.
- Second-home and luxury-estate files on 32963 often draw more documentation because the property type, occupancy, and loan size all influence pricing.
The practical result is simple: a borrower may qualify comfortably for a mainland home at one price point, then find the same household budget much tighter on a beachside property because the financing moves from standard conforming terms into a higher-cost jumbo bracket.
Portfolio Loans and Buydowns Solve Different Problems
Private banking portfolio loans can be a smart fit when conventional underwriting becomes too rigid for a strong coastal buyer. Because the lender keeps the loan rather than selling it into the secondary market, it may place more weight on liquid assets, relationship balances, trust income, business cash flow, or a borrower’s overall net worth. That flexibility can help self-employed buyers, retirees with substantial assets, or families purchasing a high-value home with nontraditional income documentation.
Still, portfolio financing is not automatically the cheapest answer. Some local borrowers can secure a better all-in payment with a conventional or jumbo loan that uses stronger documentation and a temporary or permanent rate concession. A seller-funded Interest Rate Buydowns strategy can soften the first years of ownership, but it should be tested against the long-term carrying cost of insurance, taxes, dues, and any anticipated special assessments.
Here is how local buyers should think about the tradeoff:
- Conventional/Fannie Mae or Freddie Mac underwriting: usually favors stable W-2 income, lower-risk debt ratios, and cleaner reserve requirements.
- Portfolio lending: can accept more complex income, larger assets, or higher overall liquidity in exchange for broader underwriting discretion.
- Buydowns: work best when the buyer expects to own the property long enough to benefit from the reduced early payments.
- Rate sensitivity: a small improvement in pricing can matter more on a higher-balance home, because each eighth of a point affects a much larger loan amount.
In Vero Beach, the best financing structure is rarely the one with the flashiest headline rate. It is the structure that holds up after flood insurance, condo dues, reserve requirements, and coastal maintenance are added to the monthly total.
4-Point Mortgage and Financing Due-Diligence Checklist for Local Buyers
- Confirm the loan tier before you write the offer. Ask your lender whether the expected loan amount stays within conforming limits or crosses into jumbo territory, and run both payment scenarios before committing.
- Verify the property’s flood and insurance profile. Compare AE and X zones, review the elevation certificate if available, and price homeowners, wind, and flood coverage as part of the full monthly payment.
- Study the association file. For condos and HOA communities, review dues, reserves, milestone inspections, special assessments, rental restrictions, and any pending litigation or structural work.
- Compare the full financing stack. Evaluate conventional, jumbo, portfolio, and buydown options side by side, including reserves, closing costs, appraisal expectations, and how each option affects debt-to-income ratios.
Final Considerations for Vero Beach Buyers
In Indian River County, financing decisions are shaped by more than just the headline rate. A property on the 32963 barrier island may require a different lending strategy than a mainland home because loan size, flood exposure, condo rules, reserve demands, and insurance premiums all influence the true monthly cost of ownership. Buyers who compare conforming, jumbo, and portfolio options early are in a better position to protect cash flow, preserve negotiation leverage, and avoid surprises after contract. The smartest move is to treat the mortgage conversation as part of the property search itself, not as an afterthought once the offer is already accepted.
FAQ
How much can a rate change affect buying power on a Vero Beach jumbo loan?
On a larger loan balance, even a modest rate increase can change the monthly payment enough to push a borrower over the lender’s debt-to-income threshold. In practical terms, that can reduce approval room, weaken qualifying power, or require a larger down payment to keep the deal workable.
When does a portfolio loan make more sense than conventional financing in 32963?
A portfolio loan can make more sense when the borrower has strong assets, complex income, or a property that does not fit neatly inside standard agency underwriting. It is also worth comparing when a coastal home’s insurance, dues, or documentation profile makes conventional financing less efficient. For tailored guidance and experienced local representation, connect with MacEvoy Real Estate Co. to protect your coastal investment.